

Top AI Companies in London (951)
Legora is the agentic operating system for legal work, supporting lawyers in research, review, and drafting across complex matters. It is used by more than 130,000 legal professionals at more than 2,000 leading law firms and in-house legal teams across over 80 markets.

Legora's Top Stability & Growth Strengths
Strong Revenue Growth: Reporting indicates ARR accelerated from tens of millions in 2025 to $100M+ by April 2026, with subsequent coverage citing further gains (e.g., ~$150M–$200M). This pace is repeatedly described as the clearest signal of substantial commercial momentum.
Market Expansion: Disclosures describe expansion from ~20 markets in 2025 to 40–50+ markets by 2026, with new offices across hubs including New York, Denver, Sydney, Bengaluru, Chicago, and Houston. Customer counts rose from ~250 to 800, 1,200+, and 1,480+ over 2025–26 alongside this footprint growth.
Investor Backing & Capital Strength: Financing progressed from an $80M Series B at a $675M valuation to a $550M+ Series D and extension around $5.6B within a year. This indicates strong access to capital and investor conviction to fund rapid scaling.
Apollo is a $1.6B AI-powered sales platform that helps revenue teams find and engage leads, automate outreach, manage deals, and enrich data — all in one place. Known for its industry-leading B2B database of more than 210 million contacts and 35 million companies, Apollo’s end-to-end platform helps businesses of all sizes unlock their full market potential with unparalleled precision and...

Apollo.io's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported at $150M in May 2025, with a February 2026 update indicating it was approaching $200M. External recognition like Deloitte’s Fast 500 cites very high multi-year revenue growth (e.g., 752% from 2021–2024).
Market Expansion: Customer penetration is described as nearly 100,000 paying customers by February 2026 and more than 600,000 companies served. Movement upmarket is highlighted by a stated 400% increase in enterprise accounts over the prior 12 months.
Innovation-Driven Growth: AI platform usage reportedly grew 500% year over year with 50,000+ weekly active users in 2025. Product momentum includes an AI Assistant launch, new AI integrations, and the Pocus acquisition in 2026.

AlertMedia helps organizations protect their people and businesses through all phases of an emergency. Our award-winning threat intelligence, emergency communication, and travel risk management solutions help companies of all sizes identify, respond to, and recover from critical events faster and more confidently. Our team of in-house intelligence analysts and meteorologists work around the clock to monitor thousands of data sources...

AlertMedia's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as having exceeded 40% year over year in 2022 and 273% growth over the Deloitte Fast 500 measurement period. Recent disclosures cite well over $100M in ARR and reporting of more than $100M in annual revenue.
Market Expansion: Customer footprint is reported at 3,500+ organizations across 150+ countries, with earlier periods adding 600+ customers and a London office opened to support rapid international growth. Partnerships and channel integrations are noted as expanding reach to multinational programs.
Product Line Growth: The platform has broadened through AI-powered launches (assistants, analytics, plan builders) and the acquisition of Pyrra to add social/digital threat intelligence. Continued investment in 2026, including new leadership roles focused on AI, underscores ongoing product expansion.

Datadog (NASDAQ: DDOG) is a global SaaS business, delivering a rare combination of growth and profitability. We are on a mission to break down silos and solve complexity in the cloud age by enabling digital transformation, cloud migration, and infrastructure monitoring of our customers' entire technology stacks. Built by engineers, for engineers, Datadog is used by organizations of all sizes...

Datadog's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show accelerating top-line momentum, with FY2025 up 28% and Q2 2026 revenue up 36% year over year after 32% in Q1. Management also raised 2026 revenue guidance to $4.45B–$4.47B, indicating confidence in continued expansion.
Healthy Cash Flow: Cash generation is substantial, including Q2 2026 operating cash flow of $316M and free cash flow of $279M with about a 25% free-cash-flow margin. The company also reported roughly $5.0B in cash, cash equivalents and marketable securities as of June 30, 2026.
Customer Loyalty & Retention: Expansion within the installed base is a key driver, with about 75% of the 2025 revenue increase coming from existing customers and rising multi‑product adoption. Larger accounts are also expanding, as $100K+ ARR customers grew roughly 23% year over year to ~4,720 in Q2 2026.

By automating and streamlining common accounting workflows to make them more efficient, FloQast is where accounting teams want to work so they can focus on what matters most, even when that’s just logging off on time. Whether automating reconciliations, documentation requests, or streamlining recurring accounting processes, such as the month-end close, financial reporting, or payroll, FloQast's platform enhances the way...
FloQast's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have surpassed $100M in 2023 and more than $200M by January 2026, roughly doubling in about two years. Recognition such as Deloitte Technology Fast 500 (with 289% reported multi-year revenue growth) and Inc. 5000 further underscores rapid expansion.
Market Expansion: International presence has broadened across the UK, EMEA (including DACH), and Australia/New Zealand, with continued EMEA growth noted. The customer base expanded to more than 3,500 global accounting teams by 2026, up from over 1,500 in 2021.
Investor Backing & Capital Strength: A $100M Series E in April 2024 at a reported $1.6B post-money valuation, corroborated by independent outlets, adds meaningful financial capacity. This funding is positioned to support scaling across product and international markets.
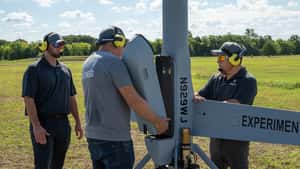
At Shield AI, you won't wait years to see your work reach the field. You'll build hardware and software that operates in the real world right now, in the hands of the people who depend on it. Hivemind, our AI pilot, has been flying since 2018. It has flown more than 30 platforms, including an F-16, and it now sits under...
Shield AI's Top Stability & Growth Strengths
Strong Revenue Growth: Company reports indicate FY2026 orders and revenue doubled year over year. Management projections point to revenue well above $500 million for 2026, signaling rapid topline acceleration.
Investor Backing & Capital Strength: Recent financings include a $1.5 billion Series G and $500 million in preferred equity at a $12.7 billion valuation. These steps indicate substantial capital access and confidence from major financial backers.
Market Expansion: Program momentum includes a U.S. Air Force production award for CCA autonomy and a U.S. Navy ISR vehicle with a high task‑order ceiling. International traction spans India, Greece, Poland, and Taiwan, alongside plans for regional offices.
Hiya is trusted by global businesses, carriers, and consumers to enable secure, engaging connections and stop unwanted calls. Hiya is pioneering the next generation of AI-powered voice intelligence with real-time analysis and an AI assistant to enhance voice protection, productivity, and call performance. Hiya connects businesses with their customers, helps carriers secure their networks, and protects people from spam and...
Hiya Inc.'s Top Stability & Growth Strengths
Strategic Partnerships: Samsung and Hiya extended their relationship through 2028, and Hiya highlights deep integrations with major operators and OEMs. Recent launches with Vodafone (UK and Ireland), Bouygues Telecom (France), DNA Finland, Telenor Sweden, Deutsche Telekom and O2 Telefónica (Germany) reinforce embedded distribution at device and network level.
Market Expansion: Hiya reports coverage in 40+ countries with network reach growing from 200M+ in 2021 to 500M–550M+ people, alongside analysis of 28B+ calls per month. Ongoing European rollouts in 2025–2026 indicate continued geographic scaling and platform utilization.
Product Line Growth: The company has broadened beyond caller ID/spam blocking into enterprise SaaS and branded calling, introducing offerings such as Hiya AI Phone and Caller Reputation. The acquisition of Loccus.ai for deepfake voice detection further expands its voice‑security portfolio.
.png)
Canoe offers first-of-its kind AI technology powering the future of alternative investments. Canoe has reimagined the future of alternative investments with cloud-based, machine-learning technology for document collection, data extraction, and data science initiatives. We transform complex documents into actionable intelligence within seconds and empower allocators with tools to unlock new efficiencies for their business. Since the beginning, we’ve maintained a focused, client-first...

Canoe's Top Stability & Growth Strengths
Strong Revenue Growth: Company disclosures indicate very strong year-over-year revenue expansion in 2023 with continued gains into 2024 alongside client growth. Investor communications also highlight a significant valuation step-up between the 2023 and 2024 financing rounds, reinforcing momentum.
Market Expansion: Expansion efforts are evident in a rapid international buildout, with notable growth across EMEA and new entries in APAC, adding many new firms and operating across numerous countries. This points to widening geographic reach and ongoing customer acquisition.
Investor Backing & Capital Strength: Capital support appears strong, including a sizable Series C led by a major institutional investor and a definitive agreement to be acquired by Bloomberg. These events suggest external validation and resources to sustain scaling.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is considered to be expanding rapidly, with recent quarters showing accelerated year-over-year gains in both total and subscription revenue. Multi-year growth at a high double-digit pace is also evident in the latest annual results.
Resilient & Sustainable Growth: Contracted revenue indicators appear robust, with total RPO at $29.0B and current RPO at $13.2B in Q2 2026. Management also raised its full-year 2026 subscription outlook, signaling confidence in continued expansion.
Innovation-Driven Growth: Newer AI offerings are gaining commercial traction, with ServiceNow AI surpassing $1 billion in annual contract value and agentic deployments scaling quickly. Large-deal activity and the count of very large customers also increased, indicating product-led expansion.


Liftoff is a leading AI-powered performance marketing platform for the mobile app economy. Our end-to-end technology stack helps app marketers acquire and retain high-value users, while enabling publishers to maximize revenue across programmatic and direct demand. Liftoff’s solutions, including Accelerate, Direct, Monetize, Intelligence, and Vungle Exchange, support over 6,600 mobile businesses across 74 countries in sectors such as gaming, social, finance,...

Liftoff's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has risen strongly across 2025–2026, with the latest quarter marking the company’s 11th consecutive period of top-line expansion. Momentum is driven by continued gains in its Core Advertising business.
Profitability: Adjusted EBITDA expanded materially, with margins improving alongside scale, indicating solid operating leverage. Recent quarters show profitability strengthening even as the business invests for growth.
Healthy Cash Flow: Operating and free cash flow increased sharply on a trailing twelve‑month basis. Cash generation supports reinvestment and a stronger balance sheet following debt reduction.
At Graphcore, we’re building the future of AI compute. We’re a team of semiconductor, software and AI experts, with deep experience in creating the complete AI compute stack - from silicon and software to infrastructure at datacenter scale. As part of the SoftBank Group, backed by significant long-term investment, we are delivering key technology into the fast-growing SoftBank AI ecosystem....

Graphcore's Top Stability & Growth Strengths
Investor Backing & Capital Strength: SoftBank ownership and subsequent capital deployments are described as materially strengthening the company’s funding base, with multiple 2025–26 share allotments and later injections supporting expansion. Evidence indicates this provides far greater financial backing than before the acquisition.
Strong Hiring & Retention: Plans to double UK headcount to around 750 and create 500 semiconductor roles in India signal substantial workforce expansion. The company also indicated immediate hiring of 100 India engineering roles, suggesting growth already underway.
Market Expansion: Announcements of a new AI Engineering Campus in Bengaluru and additional international offices point to a broader geographic footprint. These moves indicate active scaling of R&D capacity across regions.
ZS is a management consulting and technology firm that partners with companies to improve life and how we live it. We transform ideas into impact by bringing together data, science, technology and human ingenuity to deliver better outcomes for all. Founded in 1983, ZS has more than 15,000+ employees in over 40 offices worldwide.
ZS's Top Stability & Growth Strengths
Strong Hiring & Retention: Hiring and headcount are expanding, with disclosures of 15,000+ global employees, thousands of new hires, and third‑party estimates indicating continued workforce growth. Available evidence also points to active internal mobility and a recent increase in active job postings.
Market Expansion: Geographic and client footprints are broadening, with 40+ offices and 1,700+ customers across 170+ countries alongside concrete investments in new and expanded locations such as Hyderabad and Kingston. These moves indicate scaling delivery capacity in major capability centers and new regions.
Innovation-Driven Growth: The offering mix is shifting toward AI, data, technology, and platforms, including proprietary solutions and product capabilities. Strategic moves such as Salesforce-focused acquisitions and collaborations, plus a Tulip solution partnership, extend capabilities beyond traditional consulting.
Movable Ink personalizes every customer engagement through automation and artificial intelligence. The world’s most innovative brands rely on Movable Ink to maximize revenue, simplify workflow and achieve the optimal customer experience. Headquartered in New York City with 600 employees, Movable Ink serves its global client base with operations throughout North America, Central America, Europe, and Australia.
Movable Ink's Top Stability & Growth Strengths
Innovation-Driven Growth: Product announcements highlight expansion of the Da Vinci AI platform into new channels and the launch of Programmatic CRM/agentic capabilities, indicating an active cadence of AI-led features. These moves extend the company beyond its historical email-personalization focus into broader omnichannel decisioning.
Market Expansion: The company expanded Da Vinci into Europe and reported winning more than 100 new enterprise customers in the year prior to mid-2025. These signals point to increased geographic reach and deeper penetration in enterprise segments.
Investor Backing & Capital Strength: Symphony Technology Group agreed to acquire the company in June 2025 and explicitly referenced its growth and 100+ new enterprise wins as part of the rationale. This transaction represents significant institutional backing aligned to the company’s next phase of growth.
Founded in 2020 by George Sivulka and backed by Peter Thiel and Andreessen Horowitz, Hebbia powers investment decisions for BlackRock, KKR, Carlyle, Centerview, and 40% of the world’s largest asset managers. Our flagship product, Matrix, delivers industry-leading accuracy, speed, and transparency in AI-driven analysis. It is trusted to help manage over $15 trillion in assets globally. We deliver the intelligence that...

Hebbia's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue momentum is described as rapid, with the company citing 15× growth over 18 months and coverage noting roughly $13M ARR in mid-2024. Independent estimates indicate ARR scaling into the tens of millions through 2025–2026, suggesting continued top-line expansion despite the absence of audited figures.
Investor Backing & Capital Strength: A sizable $130M Series B in 2024 led by Andreessen Horowitz, bringing total funding to roughly $161M alongside a reported ~$700M valuation, signals strong capital support. This investor base and funding depth provide capacity to invest in product and go-to-market.
Market Expansion: Geographic and product scope have broadened, including expansion into the UK and Europe and additions such as agents, research capabilities, and financial-data integrations. Company-reported activity—hundreds of thousands of daily prompts, billions of pages processed, and 1,000+ use cases across finance, legal, banking, and corporate finance—points to widening reach.
Nexthink is the global leader in digital employee experience management. Our platform empowers IT teams with real-time visibility, analytics, and automation to proactively detect and resolve issues across any application, device, or network—before they affect employees. By shifting IT from reactive problem-solving to continuous optimization, Nexthink enables more than 1,300 organizations to create productive, seamless, and satisfying digital workplaces for...
Nexthink's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has scaled materially, with ARR approaching the $400M mark and leadership targeting expansion toward $1B, alongside earlier signals such as 42% YoY ARR growth and very high renewal/net expansion. Feedback suggests recent indications of ~$300–350M revenue and expanding customer/end‑user coverage reinforce continued momentum.
Investor Backing & Capital Strength: A majority investment by Vista Equity Partners at an approximately $3B valuation signals strong capital support and confidence in the company’s scaling prospects. Feedback suggests this backing, including associated financing, enables continued product and geographic expansion.
Strong Market Position & Advantage: Repeated recognition as a Leader in Gartner’s DEX Magic Quadrant (2024–2026) and Forrester’s EUEM Wave points to sustained category leadership. Large‑scale enterprise adoption (e.g., 1,500+ customers and 25M+ employees served) further entrenches competitive positioning.
Yext (NYSE: YEXT) is the enterprise agentic marketing platform. Built on the world's most comprehensive structured data platform for local businesses, Yext gives brands and their partners the visibility intelligence to win every moment of discovery – across AI and traditional search. Yext's API-first architecture connects structured data to APIs, MCP servers, and generative interfaces, so partners and developers can...

Yext's Top Stability & Growth Strengths
Profitability: Net income turned from -$27.9M in FY2025 to +$37.9M in FY2026, and adjusted EBITDA rose from $67.0M to $107.3M with margin expansion. Profitability continued into FY2027 with strong quarterly EBITDA performance.
Cost & Operational Efficiency: Operating discipline, restructuring, and reduced expenses are credited with materially improving margins and earnings despite muted top-line trends. The business has shifted from loss-making expansion to efficiency and margin expansion.
Future-Ready Strategy: Product investments and positioning around AI/agentic marketing (e.g., Scout, Corvo AI) and targeted acquisitions (e.g., Hearsay) indicate a pivot toward AI-driven search visibility and regulated-industry use cases. This suggests preparation for evolving demand rather than reliance solely on legacy listings revenue.
Bounteous is a global AI Services firm where agentic engineering and human experience converge to deliver transformative business outcomes for the enterprise. We help organizations design, build, and scale AI-driven products, platforms, and processes. With more than 5,000 team members worldwide, Bounteous delivers AI that sticks, powering adoption and outcomes that move organizations from experimentation to true transformation.

Bounteous's Top Stability & Growth Strengths
Market Expansion: The company has scaled through the 2024 Accolite merger and the 2026 Cartesian acquisition, which broaden capabilities and extend its North American and European footprint. Hiring initiatives in India and emphasis on EMEA growth further indicate a wider geographic reach.
Innovation-Driven Growth: The organization has repositioned from digital transformation toward AI services, with recent moves explicitly adding data, analytics, and enterprise AI capabilities. This shift aligns offerings with higher-growth categories.
Diversified Customer Base: Following the Accolite combination, the firm cites serving hundreds of Fortune 1000 and high-growth clients. This signals access to a broad enterprise demand base.

Hudson River Trading brings a scientific approach to trading financial products. We have built one of the world's most sophisticated computing environments for research and development. Our researchers are at the forefront of innovation in the world of algorithmic trading.
Hudson River Trading's Top Stability & Growth Strengths
Strong Revenue Growth: Trading revenue is described as reaching record levels in 2025 and again in 2026, including very large quarterly hauls. Reporting indicates momentum has accelerated alongside expansion across asset classes and regions.
Profitability: Net income is portrayed as exceptionally strong in recent quarters, signaling substantial earnings power alongside top-line gains. Observations point to operating leverage from a scalable, technology-heavy model.
Investor Backing & Capital Strength: A revised Positive outlook from a major rating agency and commentary on a growing capital base suggest a strengthening financial footing. This is reinforced by continued investment capacity, including multi-year AI infrastructure partnerships.
Genius Sports is the layer between what happens on the field and how the world engages with it. Our solutions across the global sports ecosystem are underpinned by our next generation big data and artificial intelligence platform, GeniusIQ. By ingesting and computing multiple real-time data feeds, GeniusIQ powers a wide range of functions and applications across sports performance and officiation, fan engagement,...
Genius Sports's Top Stability & Growth Strengths
Strong Revenue Growth: Reported results show consistent top-line increases through 2025 and into 2026, including a sharp acceleration in Q2 2026. Guidance was raised above $1B for 2026, underscoring momentum.
Strategic Partnerships: Long-term, often exclusive relationships with tier‑one rights holders such as the NFL (through 2029), Football DataCo/Premier League (through 2029) and the NCAA (through 2032) reinforce commercial visibility. These agreements expand distribution and underpin growth across betting and media.
Innovation-Driven Growth: Product advances like GeniusIQ, BetVision, and Second Spectrum tracking are cited as drivers of expanding media and betting solutions. This innovation push aligns with rapid Media segment growth and broader market expansion.
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue appears to be increasing over time, with evidence of substantial growth in 2022 and continued year-over-year expansion into early 2023, even as the pace moderates. Feedback suggests the business is still scaling toward a larger revenue base while transitioning to a mature growth profile.
Profitability: Independent credit commentary highlights improved profitability and a deliberate shift toward a profit-focused operating model. Feedback suggests efficiency gains and margin improvement are becoming central to the company’s stability and growth trajectory.
Innovation-Driven Growth: Ongoing AI platform investment, rising adoption of AI capabilities, and product expansion including acquisitions are cited as current growth engines. Feedback suggests these initiatives are supporting continued operational and market expansion.



