

Top Cloud Companies in London (460)
Toast is the all-in-one platform built for restaurants of all sizes. Toast provides a single platform of software as a service (SaaS) products and financial technology solutions that give restaurants everything they need to run their business, including point of sale, payments, supplier management, digital ordering and delivery, marketing and loyalty, and team management. By serving as the restaurant operating...
Toast's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is increasing at a double‑digit pace, with Q2 2026 revenue of about $1.91B up year over year. Full-year 2025 revenue also rose meaningfully to roughly $6.15B from $4.96B the prior year, indicating momentum across periods.
Profitability: Profitability is improving, as Q2 2026 net income increased to about $154M and operating income to roughly $152M from the prior year’s quarter. Recurring gross profit from subscription and fintech reached approximately $585M, showing stronger unit economics alongside scale.
Market Expansion: Customer reach is widening, with roughly 9,500 net locations added in Q2 2026 and total locations around 180,000, both higher than a year earlier. The company is also extending into retail, enterprise, international markets, and AI-enabled products such as Toast IQ.
PagerDuty, Inc. (NYSE:PD) is a global leader in digital operations management, enabling customers to achieve operational efficiency at scale with the PagerDuty Operations Cloud. The PagerDuty Operations Cloud combines AIOps, Automation, Customer Service Operations and Incident Management with a powerful generative AI assistant to create a flexible, resilient and scalable platform to increase innovation velocity, grow revenue, reduce cost, and...

PagerDuty's Top Stability & Growth Strengths
Profitability: GAAP profitability and improved operating performance are evident, with margins and income strengthening across recent periods. This trend indicates the business is becoming more earnings-efficient even as top-line expansion slows.
Healthy Cash Flow: Consistently strong free cash flow in the latest year and quarter underscores solid cash generation. This provides financial resilience and flexibility while growth initiatives are pursued.
Future-Ready Strategy: Investments in AI-driven operations, autonomous SRE agents, and incident-response automation position the company to capture emerging demand. These offerings create opportunities to deepen adoption with existing customers and attract new ones.

In 1939, Bill Hewlett and Dave Packard, college friends turned business partners, started the original Silicon Valley startup in the space of a rented Palo Alto garage. Starting with audio oscillators, the friends built the foundation for a company that would grow to become a global leader in enterprise technology. More than 75 years later, our success is exemplified through...
Hewlett Packard Enterprise's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate sales are rising sharply, with fiscal Q3 2026 revenue increasing significantly year over year and management lifting its revenue outlook for both FY2026 and FY2027. Growth is broad-based across servers, networking, and the Cloud & AI segment, underscoring strong top-line momentum.
Profitability: Operating performance has strengthened materially, with operating profit up sharply and margins expanding in the latest quarter. Guidance points to continued non-GAAP earnings growth into FY2027, suggesting improved earnings durability.
Healthy Cash Flow: Cash generation is strengthening, with free cash flow rising to about $1.0B in the latest quarter. The outlook targets at least $5B of free cash flow in FY2027, signaling robust internal funding capacity.

Datadog (NASDAQ: DDOG) is a global SaaS business, delivering a rare combination of growth and profitability. We are on a mission to break down silos and solve complexity in the cloud age by enabling digital transformation, cloud migration, and infrastructure monitoring of our customers' entire technology stacks. Built by engineers, for engineers, Datadog is used by organizations of all sizes...

Datadog's Top Stability & Growth Strengths
Strong Revenue Growth: Recent financials show accelerating top-line expansion, with quarterly revenue surpassing the billion-dollar mark and full-year results climbing meaningfully. Momentum continued into 2026, reflecting broad demand across observability, security, and AI-related offerings.
Healthy Cash Flow: Operations are generating substantial operating and free cash flow alongside growth. This pattern persisted through mid-2026, indicating efficient scaling.
Strong Market Position & Advantage: Industry evaluations repeatedly place the company as a Leader in observability and digital experience monitoring, including top positioning for execution. Recognition such as Customers’ Choice and multi-product leadership suggests deep adoption and competitive strength.
HiBob helps modern, mid-size businesses transform the way they manage people, giving HR and managers all they need to connect, engage, develop, and retain top talent. Since 2015, we’ve achieved consecutive triple-digit year-over-year growth, all backed by our amazing team of Bobbers from across the globe, making us the choice HRIS of over 4000 midsize and multinational companies. Our HR platform...
HiBob's Top Stability & Growth Strengths
Strong Revenue Growth: Feedback suggests ARR expanded from an estimated $170M in 2024 to $250M in 2025, indicating roughly mid-to-high-40% growth at scale. Additional narrative points to multi-year acceleration supported by rising customer counts and product breadth.
Investor Backing & Capital Strength: Feedback suggests a $166M investment led by Salesforce in September 2026, with reports of valuation rising to around $3.2B. This capital indicates continued confidence to fund expansion and strategic initiatives.
Product Line Growth: Feedback suggests expansion beyond core HR into payroll and FP&A through acquisitions like Pento (2024) and Mosaic (2025). These moves broaden cross-sell potential and support upmarket motion.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as rising at a strong, double‑digit pace across recent quarters and years, with subscription sales increasing alongside total revenue. Company guidance for subscription revenue was raised, reinforcing the momentum.
Resilient & Sustainable Growth: Remaining performance obligations and current contracted revenue expanded, indicating meaningful visibility into future sales. Growth in large enterprise customers and multi‑million‑dollar deals further supports durability.
Innovation-Driven Growth: AI offerings became a meaningful commercial driver as ServiceNow AI exceeded $1 billion in annual contract value and deployments accelerated. Adoption of workflow and AI products is highlighted as a primary catalyst.

The database market is big. How big? Well, according to IDC, it’ll reach $153 billion by 2027. And MongoDB is at the forefront of that innovation with thousands of customers across the globe. We empower developers and businesses to build and deploy the applications they want, wherever they want.
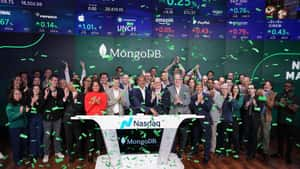
MongoDB's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has accelerated, with fiscal Q2 2027 rising 30% year over year to $771.8M after fiscal 2026 grew 23% to $2.46B. Management also raised fiscal 2027 revenue guidance to about $2.99–$3.03B.
Customer Loyalty & Retention: Existing customers are expanding spend, as net revenue retention reached 122% and customers generating at least $100,000 in ARR grew to nearly 3,000. Total customers also increased to roughly 70,600, indicating broadening adoption alongside expansion within accounts.
Healthy Cash Flow: Free cash flow nearly doubled to $137.6M in Q2 FY2027, alongside an improved non-GAAP operating margin of 24% and a swing to positive GAAP net income. Reported cash and short-term investments were approximately $2.4B at quarter-end.
Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue and annual recurring revenue each rose 25% in fiscal 2026, with fourth-quarter revenue also up 25% year over year. Management still expects continued double-digit growth in fiscal 2027, albeit at a slower pace.
Healthy Cash Flow: Operating cash flow reached about $1.13 billion and free cash flow was roughly $779.1 million in fiscal 2026. This points to robust cash generation alongside expansion.
Product Line Growth: The platform is expanding into AI security, data security, SASE, and agentic security operations. Security-for-AI bookings were reported to increase more than 50% sequentially in the fourth quarter, indicating early traction.

Managing a technology estate has never been a bigger challenge. Hardware, software, and users can be anywhere at any time, making IT environments extremely dynamic and often complex. A seemingly simple question has become terribly difficult to answer: ‘Who is using what device?’ CIO's, CTO's, IT managers, ... have to make decisions that are often based on scattered, out of date,...

Lansweeper's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A majority-stake agreement by Bridgepoint outlines funding for AI, cybersecurity capabilities, international expansion and selective acquisitions, building on the earlier Insight Partners investment. These commitments indicate ample capital support for scaling initiatives.
Product Line Growth: The Redjack acquisition added passive network discovery and application‑dependency mapping, extending the platform into cybersecurity and resilience use cases. This broadening of capabilities suggests an expanding product footprint beyond traditional IT inventory.
Strong Hiring & Retention: Workforce estimates indicate net headcount growth from the end of 2023 to the end of 2025, and the company appointed a seasoned chief revenue officer to strengthen global go‑to‑market. These moves reflect continued investment in people and commercial execution.


LogicMonitor® is the AI-first hybrid observability platform powering the next generation of digital infrastructure. LogicMonitor delivers complete visibility and actionable intelligence across on-premises, cloud, and edge environments. By anticipating issues before they strike, optimizing resources in real time, and enabling faster, smarter decisions, LogicMonitor helps IT and business leaders protect margins, accelerate innovation, and deliver exceptional digital experiences without compromise....

LogicMonitor's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have progressed from more than $300 million in June 2025 to more than $400 million by May 2026, signaling clear top-line momentum. Growth among higher‑spend enterprise accounts is also highlighted as a key contributor.
Investor Backing & Capital Strength: An $800 million equity and strategic financing round at an approximately $2.4 billion valuation is described as providing substantial capacity to fund expansion. Ongoing sponsorship by the controlling shareholder is also noted.
Product Line Growth: AI-led offerings such as Edwin AI are described as contributing a significant share of bookings with very rapid recurring‑revenue growth. The Catchpoint acquisition further extended capabilities into internet performance and digital experience monitoring.
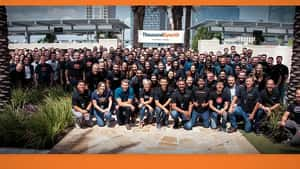
Cisco ThousandEyes is a Digital Experience Assurance platform that empowers organizations to deliver flawless digital experiences across every network – even the ones they don’t own. Powered by AI and an unmatched set of cloud, internet and enterprise network telemetry data, ThousandEyes enables IT teams to proactively detect, diagnose, and remediate issues – before they impact end- user experiences. ThousandEyes...
Cisco ThousandEyes's Top Stability & Growth Strengths
Strong Revenue Growth: Cisco’s filings indicate its Observability category is expanding, with ThousandEyes explicitly cited as a contributor to that growth. More recent updates also describe year-over-year increases for the category, reinforcing ThousandEyes’ positive revenue impact.
Product Line Growth: Ongoing releases such as AI-enabled workflows, Traffic Insights, and deeper integrations (including with Splunk) broaden ThousandEyes’ capabilities. Additions like Connected Devices and expanded cloud visibility move the product beyond traditional network monitoring into wider assurance use cases.
Market Expansion: ThousandEyes is being extended across Cisco’s ecosystem and into service-provider scenarios, increasing its reach beyond conventional enterprise IT teams. Expanded distribution through Cisco networking and observability portfolios creates additional cross-sell pathways.
Hiya is trusted by global businesses, carriers, and consumers to enable secure, engaging connections and stop unwanted calls. Hiya is pioneering the next generation of AI-powered voice intelligence with real-time analysis and an AI assistant to enhance voice protection, productivity, and call performance. Hiya connects businesses with their customers, helps carriers secure their networks, and protects people from spam and...
Hiya Inc.'s Top Stability & Growth Strengths
Market Expansion: International rollouts with major carriers in France, Sweden, Finland, the UK, and Germany, alongside coverage in 40+ countries and 550M+ people reached, point to broadening geographic presence and adoption. These developments signal accelerating distribution through network-level deployments rather than relying solely on standalone apps.
Strategic Partnerships: Multi-year agreements and new deployments with Samsung (extended through 2028) and operators such as Deutsche Telekom, O2 Telefónica, Vodafone, Bouygues Telecom, Telenor, and DNA indicate durable enterprise relationships. These tie-ups embed the platform at the carrier and device level, supporting continued commercial traction.
Product Line Growth: Expansion beyond spam detection into AI voice security, deepfake detection, branded calling, and tools like Caller Reputation and Hiya AI Phone broadens monetization paths. The Loccus.ai acquisition and subsequent feature launches illustrate ongoing investment in new capabilities.
Sonar provides the essential verification layer for the AI-driven development era, ensuring all code—whether human-written or AI-generated—is code you can trust. Today, AI coding tools are generating explosive volumes of code. This has created an "engineering productivity paradox" : faster code writing doesn't automatically lead to faster, safer software delivery. The new bottleneck is verification. Sonar solves this. Integrating code quality and...

Sonar's Top Stability & Growth Strengths
Strong Revenue Growth: Reported ARR above $430 million and descriptions of accelerated growth point to meaningful top-line expansion. Additional indicators such as broad adoption help contextualize the revenue scale, though they are adoption signals rather than direct revenue.
Strong Market Position & Advantage: Enterprise adoption across more than 75% of the Fortune 100 and a developer base exceeding seven million suggest a durable competitive position. Recognition as a Leader in Gartner’s 2026 Technical Debt Management category further underscores standing in closely aligned markets.
Innovation-Driven Growth: Expansion into AI code verification and remediation—including the Gitar acquisition and launches like Sonar Vortex and a Remediation Agent—highlights active product innovation. These moves indicate investment aimed at capturing demand from AI-assisted software development.
LogicGate® is the leading AI GRC platform for the Enterprise, helping governance, risk, and compliance teams limit surprises, strengthen resilience, augment program performance, and confidently quantify impact and business value. Built to provide a centralized view of risk and compliance, with AI intelligence woven into the platform's core, LogicGate delivers real-time insights and actionable data to help drive current business...
LogicGate's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue from large enterprise customers is described as growing nearly 50% year over year in 2025, complemented by more than 180% three-year top-line growth recognized in Deloitte’s 2025 Technology Fast 500. Inc.’s 2026 profile also cites 107% three-year growth, indicating momentum beyond a single period.
Resilient & Sustainable Growth: Six consecutive appearances on the Inc. 5000 point to sustained expansion rather than a one-off spike. Multi-year recognition across programs suggests growth durability through changing market conditions.
Innovation-Driven Growth: Ongoing investment in AI-powered GRC during 2026, including agent-based capabilities and the Config Newton product, indicates a focus on innovation to drive expansion. Feedback suggests these launches expand use cases and potential upsell, even if product releases alone do not prove revenue increases.
iManage is dedicated to Making Knowledge Work. Over one million professionals across 65+ countries rely on our intelligent, cloud-enabled, secure knowledge work platform to uncover & activate the knowledge that exists inside their business content and communications. We are continuously innovating to solve the most complex professional challenges & enable better business outcomes. Our work is not always easy but it...

iManage's Top Stability & Growth Strengths
Strong Revenue Growth: Annual recurring revenue is reported to have grown 42% year over year in 2024, with subsequent updates indicating continued momentum into 2025. Feedback suggests this trajectory is supported by the shift to subscription cloud offerings and sustained migration activity.
Market Expansion: The company added 305 new customer organizations in 2024 and 340 in 2025, indicating ongoing expansion of its installed base. Rising cloud adoption—from 71% of customers in 2025 to 78% by May 2026—reinforces broadening platform uptake.
Strong Market Position & Advantage: Adoption includes 83% of the Top Global 100 law firms, 79% of the Am Law 100, and about 40% of the Fortune 100. This entrenched presence in large enterprises supports commercial durability as the platform evolves with AI and cloud capabilities.
Cloudflare, Inc. (NYSE: NET) is the leading connectivity cloud company on a mission to help build a better Internet. It empowers organizations to make their employees, applications and networks faster and more secure everywhere, while reducing complexity and cost. Cloudflare’s connectivity cloud delivers the most full-featured, unified platform of cloud-native products and developer tools, so any organization can gain the...

Cloudflare's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has been accelerating on a quarterly basis, and full-year guidance was raised, reflecting sustained top-line momentum. Contracted demand indicators also point to continued near-term growth.
Market Expansion: Enterprise penetration is deepening with record additions of large customers and a notable footprint among major corporate ecosystems and top global websites. The customer mix is shifting upmarket, signaling successful movement into higher-value segments.
Innovation-Driven Growth: Adoption of Workers, Zero Trust, and AI-related workloads is highlighted as a key catalyst expanding use of the platform. Product breadth across security, developer services, and edge computing is supporting multi-product growth.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Quarterly revenue increased materially year over year in Q2 2026, and full-year 2025 sales also rose. The acceleration into 2026 alongside expanding user metrics signals momentum in top-line performance.
Healthy Cash Flow: Free cash flow turned positive and expanded meaningfully versus the prior year, alongside a large step-up in adjusted EBITDA. This points to improving cash generation and operating efficiency.
Diversified Revenue Streams: Subscriptions and other direct revenue grew much faster than advertising, with products like Snapchat+, Lens+, and Memories contributing significantly. This diversification reduces sole dependence on the ad cycle and broadens monetization levers.
Snyk, the leader in secure AI software development, empowers organizations to build fast and stay secure by unleashing developer productivity and reducing business risk. The company’s AI Trust Platform seamlessly integrates into developer and security workflows to accelerate secure software delivery in the AI Era. Snyk delivers trusted, actionable insights and automated remediation, enabling modern organizations to innovate without limits....
Snyk's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent analyst recognitions across 2024–2025, including Leader placements in application security testing and SAST, indicate Snyk competes at the top of its market. This standing supports commercial durability even as overall growth moderates.
Product Line Growth: Snyk Code surpassed $100M in ARR in 2024 and the DAST business recorded 245% quarter-over-quarter ARR growth after the Probely acquisition, broadening revenue contributors. Expansion across code, open source, containers, IaC, APIs, and AI security points to a wider product footprint.
Innovation-Driven Growth: Investments in AI security—such as Evo and the acquisition of Invariant Labs—reflect an active innovation agenda targeting emerging developer and AI risks. These moves are positioned as potential growth engines alongside the core platform.

Join. Grow. Lead the Future of Supply Chain. At Cleo, we don’t just integrate supply chains—we orchestrate them. As the pioneer and global leader of the Supply Chain Orchestration software category, Cleo is helping thousands of companies around the globe drive transformation, deliver excellence, and shape the future of their global operations. Whether you're joining us from outside or growing within, Cleo...

Cleo's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported to have scaled to roughly $254 million in 2025 with a sharp increase in paying subscribers to about 1.3 million, indicating substantial top-line expansion. Historical figures show a sustained multi-year trajectory upward, with independent analysis broadly corroborating the growth direction.
Customer Loyalty & Retention: Retention is described as very high alongside a customer base of 4,000–4,500+ organizations across 70+ countries on the enterprise platform, suggesting durable recurring relationships. Customer counts and multi-year renewal claims point to stable, sticky demand.
Investor Backing & Capital Strength: Capital support includes a strategic growth investment from H.I.G. Capital for the enterprise business and a cited $1 billion valuation for the consumer app, signaling institutional and market confidence. Such backing is presented as fuel for continued innovation and expansion.
Nexthink is the global leader in digital employee experience management. Our platform empowers IT teams with real-time visibility, analytics, and automation to proactively detect and resolve issues across any application, device, or network—before they affect employees. By shifting IT from reactive problem-solving to continuous optimization, Nexthink enables more than 1,300 organizations to create productive, seamless, and satisfying digital workplaces for...

Nexthink's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have more than tripled between 2021 and 2025 while profitability improved. AI-related ARR also rose from $20 million in Q1 2025 to $109 million in Q1 2026, reinforcing momentum.
Market Expansion: Reported enterprise customers grew from 1,200+ in 2024 to 1,500+ in 2025, and platform reach expanded from 15 million to 25 million endpoints/employees. International moves, including plans for Japan and South America, indicate continued geographic expansion.
Investor Backing & Capital Strength: A majority investment by Vista Equity Partners at an approximately $3 billion valuation in 2025 signals strong external confidence. This transaction follows years of scaling and provides capital support for the next phase.



