Top Data Analytics Companies in London (192)
.png)
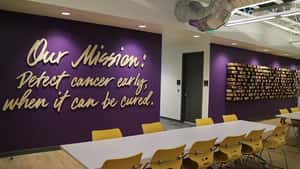
GRAIL is a healthcare company whose mission is to detect cancer early, when it can be cured. GRAIL is using the power of high-intensity sequencing, population-scale clinical studies, and state-of-the-art computer science and data science to enhance the scientific understanding of cancer biology, and to develop and commercialize pioneering products.
GRAIL's Top Stability & Growth Strengths
Strong Revenue Growth: Galleri and total revenue have risen consistently, with full-year 2025 up 17% and U.S. Galleri up 26%, followed by Q1–Q2 2026 total revenue gains of 28% and 26% alongside 50% and 35% volume growth. This cadence, including Q4 2025 Galleri revenue up 31%, indicates sustained commercial momentum after the June 2024 spin‑off.
Strategic Partnerships: Channel and platform integrations such as Epic EHR and Quest Diagnostics, plus collaborations like Samsung for Asian commercialization, are expanding access and streamlining ordering. Additional distribution wins (e.g., Priority Health employer plans and digital health channels) reinforce multi‑channel penetration for Galleri.
Investor Backing & Capital Strength: The company reports a substantial cash balance (~$861.6M as of Q2 2026) and closed a $110M equity financing with Samsung, bolstering financial flexibility. Public listing post‑spin‑off further enhances capital‑markets access to fund trials and commercialization.
Rubrik (NYSE: RBRK), the Security and AI Operations Company, leads at the intersection of data protection, cyber resilience, and enterprise AI acceleration. Rubrik Security Cloud delivers complete cyber resilience by securing, monitoring, and recovering data, identities, and workloads across clouds. Rubrik Agent Cloud accelerates trusted AI agent deployments at scale by monitoring and auditing agentic actions, enforcing real-time guardrails, fine-tuning...

Rubrik's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising rapidly across recent periods, with FY2026 results and the subsequent quarter both showing sharp year-over-year increases and strong subscription-led momentum. Management raised the FY2027 outlook following the latest quarter, underscoring continued demand.
Healthy Cash Flow: Free cash flow is meaningfully positive and improving at scale, including a healthy margin in Q1 FY2027 and a large year-over-year increase in FY2026. Improving subscription contribution margins indicate growing operating leverage.
Strong Market Position & Advantage: Independent analyst recognitions place the company among market Leaders for backup/data protection and cyber recovery, often highlighted for vision. Expanding large-customer cohorts and post-IPO scale further reinforce competitive standing.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Total revenue increased 19% in FY2026 and 16% in Q1 FY2027, while ARR reached about $2.14B, up roughly 17% year over year. Net‑new ARR also accelerated, signaling strengthening demand.
Profitability: Non‑GAAP operating income was $592M in FY2026 with ~29% margin, and Q1 FY2027 reported a ~29% margin alongside robust adjusted free cash flow. Free cash flow for FY2026 was $529M, underscoring strong operating leverage.
Resilient & Sustainable Growth: Multi‑year double‑digit ARR and revenue expansion, record large deals, and 41% organic net‑new ARR growth in Q1 FY2027 point to durable demand. A subscription‑led model and fast‑growing logs consumption support ongoing platform adoption.
We are a global investment research and financial data company with 40-plus offices across North America, Europe, Australia, and Asia. Our products and services are used daily by individual investors, financial advisors, asset managers, retirement plan providers, and institutional investors. We provide data, research, and analysis across managed investment products, publicly listed companies, private capital markets, debt securities, and real-time...
Morningstar's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue up 9.6% year over year in Q2 2026 (6.8% organic; 8.2% excluding product sunsets), with 2025 up 7.5% and year‑to‑date 2026 up 10.2% on a reported basis. Growth is led by Morningstar Credit and core data/software platforms such as Morningstar Direct and PitchBook.
Profitability: Operating and adjusted operating margins expanded in Q2 2026 alongside a 29% rise in adjusted diluted EPS to $3.10, and 2025 saw increases in operating income and adjusted operating income. These gains were supported by stronger contribution from Credit and the accretive effect of the CRSP acquisition.
Healthy Cash Flow: Free cash flow and operating cash flow increased sharply in Q2 2026, with free cash flow nearly doubling year over year. This improved cash generation coincided with active buybacks and dividends.

The database market is big. How big? Well, according to IDC, it’ll reach $153 billion by 2027. And MongoDB is at the forefront of that innovation with thousands of customers across the globe. We empower developers and businesses to build and deploy the applications they want, wherever they want.
MongoDB's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose 23% in FY2026 to about $2.46B, with Q4 FY2026 up 27% year over year and Q1 FY2027 up 25% year over year. Management guided FY2027 revenue to roughly $2.92–$2.96B, indicating continued double‑digit expansion.
Healthy Cash Flow: Operating cash flow reached about $505M in FY2026, and management highlighted “rule‑of‑40” performance in Q4. Recent updates also cite strong free cash flow in Q1 FY2027.
Innovation-Driven Growth: Atlas is the primary growth engine and reached roughly 73% of FY2026 revenue (about 75% in Q1 FY2027), with Atlas revenue growing around the high‑20s to ~30% year over year in recent periods. AI‑related additions such as vector search and Automated Embeddings (via Voyage AI) are positioned as catalysts for further adoption.
Celonis makes processes work — for people, companies, and the planet. Powered by process mining and AI, the Celonis Process Intelligence Platform integrates process data and business context to create a living digital twin of business operations. We enable thousands of companies worldwide to understand how their business actually runs and, together with their partners, build intelligent solutions that transform...

Celonis's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent market-share analysis places Celonis at the front of its category while the market itself expands. This positioning suggests the company is capturing growth in a segment it leads.
Future-Ready Strategy: External recognition for long-term growth potential signals confidence in Celonis’s strategy, innovation, and talent pipeline. This points to preparedness as the space broadens from process mining into process intelligence and AI-enabled workflows.
Strategic Partnerships: A new alliance with a major data and AI platform provider expands product integrations and go-to-market reach into enterprise AI workflows. Such ecosystem momentum supports broader adoption and commercial expansion.
Nexthink is the global leader in digital employee experience management. Our platform empowers IT teams with real-time visibility, analytics, and automation to proactively detect and resolve issues across any application, device, or network—before they affect employees. By shifting IT from reactive problem-solving to continuous optimization, Nexthink enables more than 1,300 organizations to create productive, seamless, and satisfying digital workplaces for...

Nexthink's Top Stability & Growth Strengths
Strong Market Position & Advantage: Repeated Leader placements in Gartner’s DEX Magic Quadrant (2024–2026) and Forrester’s 2024 EUEM Wave indicate durable competitive standing and sustained category momentum. These recognitions coincide with communications citing 1,200–1,500+ customers and 20M+ endpoints, underscoring broad enterprise adoption.
Product Line Growth: New offerings such as Adopt on Infinity (2025) and the Spark personal IT agent (2026), plus integrations like GoTo/Rescue and a government-focused AWS Marketplace listing, expand use cases and routes to market. The 2024 acquisition of AppLearn further broadened capabilities into digital adoption.
Investor Backing & Capital Strength: A late‑2025 majority investment by Vista Equity Partners at an approximately $3B valuation signals strong external confidence and provides resources for scaling. This step-up from the 2021 round supports continued product and go‑to‑market execution.
TransUnion is a global information and insights company that makes trust possible by ensuring that each consumer is reliably and safely represented in the marketplace. We do this by having an accurate and comprehensive picture of each person. This picture is grounded in our legacy as a credit reporting agency which enables us to tap into both credit and public record...
TransUnion's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is advancing at a double‑digit pace in early 2026, with successive quarters outperforming internal targets and full‑year guidance raised. Momentum is driven by U.S. Financial Services and improving International trends.
Profitability: Earnings are expanding, with adjusted EBITDA and adjusted EPS up year over year and full‑year guidance implying further gains. Absolute EBITDA improved even as the company invested and integrated recent acquisitions.
Market Expansion: Reach is widening through improved performance in Canada, the U.K., and India, alongside completed acquisitions in Mexico and a mobile division that extend capabilities. These moves contributed to stronger reported results and a higher outlook.

Together, we power advertising that enables billions of people to stay informed, entertained, and connected. We introduce them to new ideas, products, and services that make their lives better. And we help media owners of all sizes realize their full potential. That’s a lot — that’s the power of advertising. But it’s only possible with great technology. And that’s where Magnite...
Magnite's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose 11% year over year in Q2 2026, while contribution ex‑TAC increased 17% and management raised full‑year 2026 growth targets. Recent periods also show steady gains, including FY2025 revenue up about 7% and contribution ex‑TAC up 10%.
Profitability: Adjusted EBITDA grew 30% year over year in Q2 2026 with a 37% margin, and net income increased to $19.4M from $11.1M. FY2025 adjusted EBITDA rose 18%, indicating expanding operating leverage.
Strong Market Position & Advantage: CTV momentum is supported by broad‑based publisher demand and SpringServe differentiation, with CTV contribution ex‑TAC up 36% to $97.1M and reaching 51% of total. Company materials consistently position the firm as the largest independent SSP and a top player in CTV.

Nasuni is a leading unstructured data platform for enterprises where file data is mission-critical for both people and AI. We power the operational file layer where work happens — helping organizations manage, protect, and activate data so teams can work smarter, reduce costs, and operate securely without limits. Built on a patented architecture that fuses cloud object storage with enterprise...

Nasuni's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported to have grown 26% in FY2024, alongside roughly 30% ARR growth in 2023 after surpassing the $100M milestone in 2022. This indicates sustained top-line expansion across consecutive years.
Profitability: The company reports remaining profitable and cash‑flow positive while growing in FY2024. This suggests operational discipline alongside expansion.
Investor Backing & Capital Strength: A July 2024 majority investment led by Vista Equity Partners valued the company at about $1.2B, with participation from TCV and KKR. This financing signals external confidence and provides resources for further expansion.
InterSystems builds the software that makes complex systems work—reliably, securely, and at scale. For more than 45 years, we’ve been the information engine behind some of the world’s most mission-critical applications in healthcare, government, and business. Our data management, integration, and analytics technologies help organizations connect disparate systems, turn data into insight, and deliver better outcomes. From enabling interoperable healthcare and...

InterSystems's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Growth is described as measured and predictable, with signals such as modest headcount expansion, sustained operating scale, and continued momentum rather than volatility.
Innovation-Driven Growth: Recent major releases across IRIS/IRIS for Health/Health Connect and new AI-focused offerings indicate ongoing R&D velocity that broadens capabilities and use cases.
Strong Market Position & Advantage: Repeated industry accolades for Shared Care Records/HIE and regional acute EHRs in 2026 point to durable competitive standing in core healthcare markets.

Liftoff is a leading AI-powered performance marketing platform for the mobile app economy. Our end-to-end technology stack helps app marketers acquire and retain high-value users, while enabling publishers to maximize revenue across programmatic and direct demand. Liftoff’s solutions, including Accelerate, Direct, Monetize, Intelligence, and Vungle Exchange, support over 6,600 mobile businesses across 74 countries in sectors such as gaming, social, finance,...

Liftoff's Top Stability & Growth Strengths
Strong Revenue Growth: Management disclosed 11 consecutive quarters of top-line expansion as of Q2 2026, with guidance indicating continued increases post‑IPO. Observations across filings and coverage describe multi‑quarter momentum rather than a one‑off spike.
Investor Backing & Capital Strength: A completed IPO and a prior minority investment from General Atlantic alongside Blackstone signal institutional confidence and provide balance‑sheet flexibility. Proceeds were used in part to reduce debt, supporting capacity for further expansion.
Innovation-Driven Growth: The Cortex AI platform is presented as a core differentiator driving performance gains across a unified DSP/SSP stack. Product updates and shortened learning cycles are highlighted as catalysts for advertiser and publisher adoption.

Veeva is the global leader in cloud software for the life sciences industry. Committed to innovation, product excellence, and customer success, Veeva serves more than 1,000 customers, ranging from the world’s largest pharmaceutical companies to emerging biotechs. As a Public Benefit Corporation, Veeva is committed to balancing the interests of all stakeholders, including customers, employees, shareholders, and the industries it...

Veeva's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at a double‑digit pace across recent quarters and the latest fiscal year, with momentum reflected in higher quarterly results and a raised full‑year outlook. Near‑term guidance also points to continued expansion through the remainder of the year.
Profitability: Profitability has expanded alongside growth, with operating income and earnings increasing meaningfully in the latest quarter. A subscription‑heavy mix and higher full‑year operating income guidance support margin durability.
Strong Market Position & Advantage: Position in life‑sciences CRM remains dominant, with a very large share of biopharma seats cited by management and many top‑20 pharmas live on next‑gen Vault CRM. Broad adoption across Development and Quality Clouds and continued big‑pharma commitments reinforce competitive advantage.

Analytic Partners is a proven global leader in measurement and optimization. Our adaptive solutions integrate proprietary technology powered by the latest data science delivered through our platform and high-touch consulting. We enable deeper business understanding to support better, faster decisions. In "The Forrester Wave™: Marketing Measurement and Optimization Solutions, Q1 2020", Analytic Partners was named a Leader and was top...


Experian unlocks the power of data to create opportunities for consumers, businesses and society. During life’s big moments – from buying a home or car, to sending a child to college, to growing a business exponentially by connecting it with new customers – we empower consumers and our clients to manage data with confidence so they can maximize every opportunity. We gather,...
Experian's Top Stability & Growth Strengths
Strong Revenue Growth: Feedback suggests Experian continues to post mid- to high-single-digit organic growth alongside double-digit total growth at constant or actual rates. Management maintained or raised FY26 guidance to the top end of prior ranges, indicating sustained momentum.
Profitability: Observations indicate Benchmark EBIT increased at a double-digit rate in the latest half with margin expansion. This profit progression complements broad-based growth across regions and both B2B and Consumer Services.
Diversified Revenue Streams: Feedback suggests expansion beyond core credit into decisioning/analytics, identity and fraud, health, and consumer services is reducing reliance on credit cycles. Recent updates highlight growth across both B2B and Consumer Services, supported by acquisitions and third-party recognition in identity verification.

App Annie delivers the most trusted app data and insights for your business to succeed in the global app economy. Over 1 million registered members rely on App Annie to better understand the app market, their businesses and the opportunities around them. The company is headquartered in San Francisco with 15 global offices. App Annie has received $1


We passionately believe in the power of technology to make a difference. Chris and David, both software engineers, founded Beacon in 2017 to build a new kind of charity CRM using the latest technology and design principles. Now hundreds of innovative charities around the world trust Beacon to run their core technology infrastructure. Animal welfare, human rights, disaster relief, cancer support -...

Supermicro (SMCI), the leading innovator in high-performance, high-efficiency server technology is a premier provider of advanced server Building Block Solutions® for Data Center, Cloud Computing, Enterprise IT, Hadoop/Big Data, HPC and Embedded Systems worldwide. Supermicro is committed to protecting the environment through its “We Keep IT Green®” initiative and provides customers with the most energy-efficient, environmentally-friendly solutions available on the...
Supermicro's Top Stability & Growth Strengths
Strong Revenue Growth: Recent quarters show net sales accelerating sharply, including record results and raised full-year guidance to at least $40 billion. Sequential momentum and an earnings beat underscore ongoing top-line expansion tied to AI server demand.
Strong Market Position & Advantage: The company is seen as a top-tier global server vendor and a clear leader in AI-optimized systems. Expanded rack-scale and liquid-cooled portfolios, plus growing global manufacturing capacity, reinforce competitive standing.
Strategic Partnerships: Close alignment with leading GPU providers, including early access to next-generation platforms, underpins rapid time-to-market and substantial AI system orders. These relationships have been central to the company’s accelerated growth in AI infrastructure.

Metyis is a global firm that specializes in AI & Data, Digital Commerce, Marketing, and Design solutions, alongside advisory services. They focus on long-term partnerships to drive sustainable growth and performance for their clients through data-driven decision-making and integrated digital strategies, operating with a diverse, global talent pool across multiple international locations.