

Top Software Companies in London (2,850)
Legora is the agentic operating system for legal work, supporting lawyers in research, review, and drafting across complex matters. It is used by more than 130,000 legal professionals at more than 2,000 leading law firms and in-house legal teams across over 80 markets.

Legora's Top Stability & Growth Strengths
Strong Revenue Growth: Reporting indicates ARR accelerated from tens of millions in 2025 to $100M+ by April 2026, with subsequent coverage citing further gains (e.g., ~$150M–$200M). This pace is repeatedly described as the clearest signal of substantial commercial momentum.
Market Expansion: Disclosures describe expansion from ~20 markets in 2025 to 40–50+ markets by 2026, with new offices across hubs including New York, Denver, Sydney, Bengaluru, Chicago, and Houston. Customer counts rose from ~250 to 800, 1,200+, and 1,480+ over 2025–26 alongside this footprint growth.
Investor Backing & Capital Strength: Financing progressed from an $80M Series B at a $675M valuation to a $550M+ Series D and extension around $5.6B within a year. This indicates strong access to capital and investor conviction to fund rapid scaling.
Fusion Risk Management is recognized as the most innovative and fastest growing provider of cloud-based enterprise software for business continuity risk management, IT disaster recovery and crisis management. Fusion is transforming the industry and has been named a leader in Gartner's Magic Quadrant for Business Continuity Management software.
Fusion Risk Management's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A majority investment by Great Hill Partners in 2023, with Vista Equity Partners remaining a significant stakeholder, is described as funding to accelerate go-to-market, product innovation, and both organic and inorganic growth. This private-equity support positions the company to underwrite expansion initiatives.
Market Expansion: Appointing a leader to drive growth across EMEA and APAC in 2026 and adding a CRO (2025) and CMO (2026) to scale global revenue indicate widening geographic and go-to-market reach. Company communications highlight continued investment in international presence and partner ecosystems.
Product Line Growth: Announcements in 2025–2026 introduce new offerings such as AI-enabled capabilities, Recovery Optimization, and the Enterprise Resilience Decision System. This steady release cadence signals an expanding portfolio aligned to operational resilience use cases.
.jpg)
At Braze, we believe in the passion of our people. We seek to ignite that passion by setting high standards, championing teamwork, and creating work-life harmony. We thrive when people add their unique perspectives to our ever-growing teams—and we strive to empower you to make an impact that fuels both you, and our business.
Braze's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased solidly year over year in both the latest quarter and the full fiscal year, with momentum characterized as robust and consistent across recent periods. Company materials indicate the expansion is driven by contributions from both existing and newly added customers.
Healthy Cash Flow: Free cash flow turned positive and rose meaningfully, alongside improvements in non-GAAP operating income. These trends indicate improving cash profitability even as GAAP profitability has yet to be reached.
Customer Loyalty & Retention: Net retention indicates expansion within existing accounts, and the cohort of larger enterprise customers has grown. Together, these signals point to durable upsell and cross-sell within the installed base.
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Operating income has risen materially alongside growth, with the latest quarter reporting meaningful GAAP and adjusted operating profits and expanding margins. This indicates the business is scaling while improving earnings quality.
Resilient & Sustainable Growth: Gross profit is expanding at a strong, accelerating pace, with both Cash App and Square contributing and management raising full‑year outlooks. Longer‑term disclosures also highlight multi‑year compounding in gross profit per user across ecosystems.
Cost & Operational Efficiency: A leaner organizational structure and disciplined spending have driven record adjusted operating margins and improved operating leverage. Efficiency gains appear to be a second engine alongside revenue drivers.
HiBob helps modern, mid-size businesses transform the way they manage people, giving HR and managers all they need to connect, engage, develop, and retain top talent. Since 2015, we’ve achieved consecutive triple-digit year-over-year growth, all backed by our amazing team of Bobbers from across the globe, making us the choice HRIS of over 4000 midsize and multinational companies. Our HR platform...
HiBob's Top Stability & Growth Strengths
Strong Revenue Growth: ARR exceeded $100M in 2023 and was later cited around $250M+ in 2025, with some 2026 reporting referencing $400M+ annualized revenue. This reflects multi-year expansion in recurring revenue and an increasing average revenue per customer as the company moved upmarket.
Market Expansion: Customer count grew from roughly 1,500 in 2021 to about 5,000 by 2025–2026, and the company expanded operations across the US, Europe, Australia, and Canada. This indicates broader geographic reach and deeper penetration in its target segments.
Investor Backing & Capital Strength: Successive late-stage financings—including $150M rounds in 2021–2023 and a $166M Salesforce-led investment in 2026—underscore continued access to capital. These rounds were paired with rising valuations and were described as supporting ongoing expansion and AI-related capabilities.
Bringg is the leading Delivery Management Platform -- optimizing last mile delivery, fulfillment, and returns for retailers and carriers worldwide. Bringg transforms delivery into a competitive advantage for 800+ customers, increasing order capacity, reducing costs, and ensuring branded customer experiences, handling over 200 million orders annually.

Bringg's Top Stability & Growth Strengths
Product Line Growth: Recent launches in 2025–2026, including Dynamic Delivery Slots and AI-powered Predictive Time on Site, point to continued platform expansion. The latter was rolled out to the existing base of 800 customers, indicating active feature delivery at scale.
Market Expansion: Bringg reports 800+ customers across 70+ countries and a network of 250+ carriers. Leadership additions in 2026 for EMEA and North America, with the NA role spanning sales and customer success, align with an ongoing regional build-out.
Investor Backing & Capital Strength: Total funding is approximately $184.5M, including a $100M Series E in 2021 at about a $1B valuation. This signals substantial investor support to underwrite growth initiatives.
Snyk, the leader in secure AI software development, empowers organizations to build fast and stay secure by unleashing developer productivity and reducing business risk. The company’s AI Trust Platform seamlessly integrates into developer and security workflows to accelerate secure software delivery in the AI Era. Snyk delivers trusted, actionable insights and automated remediation, enabling modern organizations to innovate without limits....
Snyk's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Revenue and ARR continued to rise, with ARR surpassing $300M by 2025 and revenue increasing in 2024. Feedback suggests growth has moderated from earlier hypergrowth into a steadier, efficiency‑focused trajectory while the customer base expanded to 4,500+.
Product Line Growth: Snyk Code reached $100M in ARR and newer offerings such as DAST and AI‑focused products (e.g., Evo) showed strong momentum. These developments indicate the platform is extending beyond its original core into additional security categories.
Market Expansion: Enterprise adoption intensified, with that segment driving a large share of new additions and AI security opening fresh routes to demand. Customer counts grew materially from 2024 into 2025, signaling broader market reach.

Samsara (NYSE: IOT) is the pioneer of the Connected Operations® Platform, which is an open platform that connects the people, devices, and systems of some of the world’s most complex operations, allowing them to develop actionable insights and improve their operations. With tens of thousands of customers across North America and Europe, Samsara is a proud technology partner to the...

Samsara's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at around 30% year over year across recent quarters and fiscal periods, indicating continued expansion at scale. Growth is not primarily a currency effect and has been maintained across multiple updates.
Profitability: GAAP profitability has been achieved for multiple consecutive quarters, with operating income turning positive versus a loss a year earlier. Margin expansion and improved free cash flow underscore operating leverage.
Resilient & Sustainable Growth: Growth has been sustained at roughly the same pace across recent quarters and the prior fiscal year rather than spiking in a single period. Large-customer momentum and multi-product adoption underpin this consistency.
Nasuni is a leading unstructured data platform for enterprises where file data is mission-critical for both people and AI. We power the operational file layer where work happens — helping organizations manage, protect, and activate data so teams can work smarter, reduce costs, and operate securely without limits. Built on a patented architecture that fuses cloud object storage with enterprise...

Nasuni's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue grew 26% year over year in FY2024. ARR increased 30% in 2023 after crossing the $100M threshold in 2022.
Profitability: Operations remained profitable and cash‑flow positive in FY2024 while the organization expanded to just under 600 employees.
Investor Backing & Capital Strength: A July 2024 majority investment led by Vista Equity Partners (with TCV and KKR) valued the company at about $1.2B. This reflects substantial external capital support for continued expansion.

Wise is a global technology company, building the best way to move and manage the world's money. With Wise Account and Wise Business, people and businesses can hold 40 currencies, move money between countries and spend money abroad. Large companies and banks use Wise technology too; an entirely new network for the world's money. Launched in 2011, Wise is one...
Wise's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue increased 19% in FY2026 to about $2.5bn and rose a further 25% year over year to $714m in Q1 FY2027, indicating continued top-line momentum. Growth is broad-based alongside rising customers and cross-border volumes.
Profitability: Income before tax reached roughly $660m in FY2026, equating to a 26% margin while volumes and usage scaled. Profitability held even as the company reduced take rates to remain competitive.
Diversified Revenue Streams: Card spend grew 37% to ~$44bn and customer holdings rose ~40% to ~$39bn in FY2026, with card and other revenue also expanding, indicating monetization beyond transfer fees. Wise Platform partnerships with banks further extend revenue sources beyond direct consumer transfers.
iManage is dedicated to Making Knowledge Work. Over one million professionals across 65+ countries rely on our intelligent, cloud-enabled, secure knowledge work platform to uncover & activate the knowledge that exists inside their business content and communications. We are continuously innovating to solve the most complex professional challenges & enable better business outcomes. Our work is not always easy but it...

iManage's Top Stability & Growth Strengths
Strong Revenue Growth: Annual recurring revenue is described as rising sharply over recent periods with continued uplift into the following year. These signals point to a scaling recurring-revenue model rather than one-off sales.
Market Expansion: Hundreds of new customer logos were added across successive years, with net customer growth and significant increases in cloud usage across regions such as Asia and ANZ. This reflects expansion beyond North America and deeper penetration within the installed base.
Innovation-Driven Growth: Rapid cloud migration and the rollout of AI capabilities (e.g., Ask iManage, AI Enrichment, Insight+) are portrayed as key adoption catalysts. These innovations appear to be driving multi-solution uptake and greater platform stickiness among enterprises.
Sonar provides the essential verification layer for the AI-driven development era, ensuring all code—whether human-written or AI-generated—is code you can trust. Today, AI coding tools are generating explosive volumes of code. This has created an "engineering productivity paradox" : faster code writing doesn't automatically lead to faster, safer software delivery. The new bottleneck is verification. Sonar solves this. Integrating code quality and...

Sonar's Top Stability & Growth Strengths
Strong Revenue Growth: ARR has surpassed $430 million with accelerated growth, and expectations of 22–23% revenue increases in 2026–27 reinforce ongoing momentum. This scale is bolstered by tens of thousands of paying customers and broad enterprise adoption, including a large share of Fortune 100 companies.
Innovation-Driven Growth: New AI-centric offerings (e.g., Sonar Vortex and a SonarQube Remediation Agent) and the 2026 acquisition of Gitar extend the platform into AI-native code verification and review. This product cadence signals active investment to capture emerging developer and DevSecOps use cases.
Investor Backing & Capital Strength: A $412 million financing at a $4.7 billion valuation led by Advent International and General Catalyst, with Insight Partners and Permira, provides resources to scale globally. Stated plans to pursue $1 billion in revenue underline sustained access to growth capital.
.png)
Wasabi is on a mission to store all the world’s data by making data storage simple, affordable, predictable, and secure. If you have data to store, whether it’s backups, medical images, surveillance videos, financial data, multimedia, or scientific data, our pledge is to always be the cheapest, fastest, most secure and reliable cloud storage in the world. It’s all we...

Wasabi Technologies's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Funding rounds including $70M in January 2026 at a $1.8B valuation and a subsequent $250M credit facility signal strong access to capital. Company communications tie this financing to scaling its cloud‑storage platform, global footprint, and AI infrastructure.
Market Expansion: Expansion to 16 storage regions serving customers in 100+ countries, alongside growth from 40,000+ customers (2022) to 90,000+ (2024) and then 100,000+, indicates broadening reach. EMEA was cited as achieving approximately 77% year‑over‑year ARR growth under regional leadership.
Product Line Growth: A dedicated AI business and offerings such as Wasabi Fire and AiR, plus the acquisition of Seagate’s Lyve Cloud, point to active broadening of capabilities. More than 3 exabytes under management further reflects scaling usage across emerging workloads.
Accuris gives engineers trusted answers, not just access. Our Engineering Intelligence platform combines verified data, actionable insights, and purpose-built workflows — so technical and business leaders can move faster, reduce risk, and make decisions they can defend.

Accuris's Top Stability & Growth Strengths
Strong Revenue Growth: Accuris reported it “substantially accelerated revenue growth” in 2024 and was on track to exceed its financial targets. It also described “exceptional momentum” in Q1 2025.
Product Line Growth: The company expanded its portfolio with Accuris Thread in 2025 and, in 2026, launched AI Assistant, BOM Intelligence, Change Impact Analysis, and a broader Engineering Intelligence platform. These moves indicate continued investment and expansion.
Market Expansion: Operational scale grew with a new Denver headquarters and offices in the UK, India, Malaysia, and Japan, alongside global headcount reaching 1,000+ across 20 countries. Accuris also reports 6,500+ organizations and 900,000 users, up from earlier disclosures.
Citadel Securities is a technology-driven, next-generation global market maker. We provide institutional and retail investors with world-class liquidity, competitive pricing and seamless front-to-back execution in a broad array of financial products. Our teams of engineers, traders and researchers harness leading-edge quantitative research and the accelerating power of compute, machine learning and AI to power our analytics and tackle the market’s...
Citadel Securities's Top Stability & Growth Strengths
Strong Revenue Growth: Reported 2025 trading revenue rose to $12.2B from $9.7B in 2024, and 2026 featured record quarters such as a $7.3B Q2, indicating material topline expansion. EBITDA was also reported higher in 2025, reinforcing financial momentum.
Strong Market Position & Advantage: The company indicates it executes a substantial portion of daily U.S. equity and retail trading volumes and holds a top rank on Tradeweb for U.S. Treasury flows, underscoring entrenched scale. Leadership in listed options and as an NYSE Designated Market Maker further points to durable competitive advantage.
Market Expansion: New initiatives such as launching a High Touch Equities business in late 2025, opening an Amsterdam office in 2026, and operating across 50+ equity and fixed‑income markets signal active expansion. Ongoing hiring—1,800+ employees, dozens of open roles across regions, and the firm’s largest intern class—suggests continued investment in capacity.
It's simple, at DraftKings, we believe life is more fun when you're in on the action. For that reason, we’re committed to responsibly creating the world’s favorite games and betting experiences. We’re developing the most innovative and entertaining real money products and offers; to forever transform how people experience sports; to be a fully vertically integrated sports betting operator. It's...
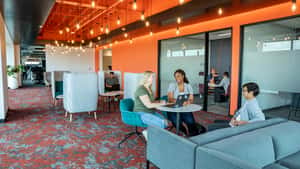
DraftKings's Top Stability & Growth Strengths
Strong Revenue Growth: Reported results show revenue rising from $3.67B (2023) to $4.77B (2024) to $6.05B (2025), with early 2026 revenue and guidance pointing to further gains. Q1 2026 continued to grow year over year, alongside expanding sportsbook handle and average monthly payers.
Profitability: Reported results show Adjusted EBITDA improving from $181M (2024) to $620M (2025) and a shift to positive GAAP net income in 2025. Guidance indicates substantial Adjusted EBITDA for 2026.
Product Line Growth: Company disclosures describe rising iGaming revenue in 2025 and the launch of new offerings like Predictions and a consolidated “super app.” These additions broaden the business beyond traditional sportsbook and DFS.
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
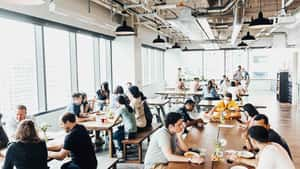
Qualtrics's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue appears to be increasing over time, with evidence of substantial growth in 2022 and continued year-over-year expansion into early 2023, even as the pace moderates. Feedback suggests the business is still scaling toward a larger revenue base while transitioning to a mature growth profile.
Profitability: Independent credit commentary highlights improved profitability and a deliberate shift toward a profit-focused operating model. Feedback suggests efficiency gains and margin improvement are becoming central to the company’s stability and growth trajectory.
Innovation-Driven Growth: Ongoing AI platform investment, rising adoption of AI capabilities, and product expansion including acquisitions are cited as current growth engines. Feedback suggests these initiatives are supporting continued operational and market expansion.
Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising from $1.62B in FY2023 to $2.17B in FY2024, $2.67B in FY2025, and about $3.35B in FY2026, with Q4 FY2026 up 25% year over year. This trajectory, alongside mid‑20% ARR growth, indicates continued expansion rather than a stall.
Healthy Cash Flow: Cash generation is growing, with free cash flow rising to about $779M in FY2026 and a free‑cash‑flow margin near 23%. Non‑GAAP operating metrics, including an ~80% gross margin, underscore operating leverage.
Strong Market Position & Advantage: Industry evaluations list the company as a Leader in the 2026 Gartner Magic Quadrants for both SSE and SASE, with five consecutive years of SSE leadership. Expanding large‑enterprise adoption and thousands of customers support a durable position in its core zero trust/SSE markets.
Justworks is a cloud-based software platform that takes the busyness out of growing a business and alleviates the unknown. We've combined a simple platform and exceptional 24/7 customer service to help entrepreneurs and businesses grow with confidence by giving them access to corporate-level benefits, automated payroll, HR tools, and compliance support— all in one place.
Justworks's Top Stability & Growth Strengths
Strong Revenue Growth: Company statements describe being on track for higher net revenue, and earlier filings documented substantial year-over-year expansion. Additional references point to rising contribution metrics over recent years.
Customer Loyalty & Retention: Company updates highlight record-high satisfaction and retention alongside a recent step-up in new-customer signups. These signals point to a stable, expanding customer base.
Product Line Growth: The business continues broadening its offering beyond core PEO into payroll, benefits, HR tools, and international employment, described under a “One Justworks” strategy. New capabilities and partnerships indicate ongoing investment in breadth.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is considered to be expanding rapidly, with recent quarters showing accelerated year-over-year gains in both total and subscription revenue. Multi-year growth at a high double-digit pace is also evident in the latest annual results.
Resilient & Sustainable Growth: Contracted revenue indicators appear robust, with total RPO at $29.0B and current RPO at $13.2B in Q2 2026. Management also raised its full-year 2026 subscription outlook, signaling confidence in continued expansion.
Innovation-Driven Growth: Newer AI offerings are gaining commercial traction, with ServiceNow AI surpassing $1 billion in annual contract value and agentic deployments scaling quickly. Large-deal activity and the count of very large customers also increased, indicating product-led expansion.



