

Top Tech Companies in London (7,386)
At Crunchyroll, we deliver what anime fans love—anytime, anywhere. With the world’s largest anime streaming library, we connect fans to the stories, characters, and creators they love. But Crunchyroll is more than just a destination to watch anime—it's a global ecosystem where anime lives and breathes beyond the screen. From streaming and theatrical releases to merch, games, news, events, and music, we...

Crunchyroll's Top Stability & Growth Strengths
Strong Revenue Growth: Paid subscribers increased from over 17 million to over 21 million as of March 31, 2026, and Sony cited higher revenues from Crunchyroll mainly due to paid-subscriber growth with guidance pointing to further gains. This indicates ongoing top-line momentum specifically attributed to the service within Sony’s Pictures segment.
Strong Market Position & Advantage: Crunchyroll is framed as the leading dedicated anime platform with the world’s largest anime library, broad global availability, and the consolidation of Funimation, and is positioned alongside Netflix as a dominant player in overseas anime streaming. This scale and catalog depth support acquisition and retention across many markets.
Future-Ready Strategy: Sony positions anime—and Crunchyroll specifically—as a core growth pillar, with initiatives spanning streaming, e‑commerce/merch, games, and manga plus cross‑company IP synergies. This integrated approach is intended to deepen monetization and expand fan touchpoints.

At Graphcore, we’re building the future of AI compute. We’re a team of semiconductor, software and AI experts, with deep experience in creating the complete AI compute stack - from silicon and software to infrastructure at datacenter scale. As part of the SoftBank Group, backed by significant long-term investment, we are delivering key technology into the fast-growing SoftBank AI ecosystem....

Graphcore's Top Stability & Growth Strengths
Investor Backing & Capital Strength: SoftBank’s 2024 acquisition and subsequent 2026 equity issuances indicate robust financial support and active recapitalization. Parent materials group Graphcore with Arm and Ampere in a new AI Computing segment, signaling ongoing strategic backing.
Strong Hiring & Retention: Plans to double UK headcount to around 750 and create 500 semiconductor roles in India, alongside active 2026 careers materials, point to sustained hiring momentum. A July 2026 update described approaching 1,000 employees and new development centers in Austin and Bengaluru, with expansion in Taiwan, Poland, and the UK.
Market Expansion: The opening of an AI Engineering Campus in Bengaluru and stated priorities in Japan and the Middle East show a widening geographic footprint. Company communications position India as a central hub with up to £1bn of investment over the next decade.

Akeneo is the Product Experience (PX) company and global leader in agentic-first Product Cloud solutions, providing the foundational operating system for the AI-powered commerce era. With its Product Cloud, Akeneo enables brands, manufacturers, distributors, and retailers to centralize, govern, and orchestrate their product information, transforming fragmented data into trusted, actionable assets. With the integration of PricingHUB, Akeneo extends its platform...

Akeneo's Top Stability & Growth Strengths
Market Expansion: Public materials indicate customer counts rising from 500+ in 2021 to more than 1,000 by mid‑2025, suggesting steady adoption. Partner motions such as becoming a Shopify Premium Partner in 2025 further extend reach and implementation capacity.
Product Line Growth: Acquisitions of Unifai (2023) and PricingHUB (2026) expand the Product Cloud from core PIM/PXM into AI‑driven enrichment and pricing, broadening wallet share opportunities. A continued 2025–2026 release cadence (e.g., AI agents, CDN, data architect enhancements) reinforces an expanding offering.
Investor Backing & Capital Strength: A $135M Series D in March 2022 underpins subsequent platform launches and acquisitions, signaling capacity to execute on product and international initiatives. This capital base supports measured expansion.
Citadel Securities is a technology-driven, next-generation global market maker. We provide institutional and retail investors with world-class liquidity, competitive pricing and seamless front-to-back execution in a broad array of financial products. Our teams of engineers, traders and researchers harness leading-edge quantitative research and the accelerating power of compute, machine learning and AI to power our analytics and tackle the market’s...
Citadel Securities's Top Stability & Growth Strengths
Strong Revenue Growth: Recent disclosures point to record annual and early‑year trading results in 2025–2026, signaling sustained top‑line momentum. Company communications also highlight elevated platform activity in options and expanded client analytics, reinforcing growth.
Market Expansion: A new Amsterdam office and recent build‑outs in Tokyo and Sydney indicate active geographic scaling across Europe and Asia‑Pacific. Increased global hiring across trading, engineering, and research supports deeper regional coverage and client reach.
Strong Market Position & Advantage: Materials emphasize a leading role in U.S. equities and retail order flow alongside prominent standings in U.S. Treasuries and investment‑grade credit. Record retail options activity and investment in high‑touch coverage integrated with electronic scale suggest durable competitive advantages.
It's simple, at DraftKings, we believe life is more fun when you're in on the action. For that reason, we’re committed to responsibly creating the world’s favorite games and betting experiences. We’re developing the most innovative and entertaining real money products and offers; to forever transform how people experience sports; to be a fully vertically integrated sports betting operator. It's...

DraftKings's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased from $3.67B (2023) to $6.05B (2025), with late‑2025 and early‑2026 showing strong year‑over‑year gains. Management continues to guide 2026 revenue above the 2025 level.
Profitability: Profitability is emerging with the first full‑year net income in 2025 and an adjusted EBITDA outlook that implies further improvement in 2026. Early 2026 also included a profitable first quarter despite later variability.
Strong Market Position & Advantage: Market position remains top‑two in U.S. online sportsbook, and usage share moved higher into Q1 2026, narrowing the gap with FanDuel. Independent product testing has also placed the app at or near the top of the category.
Movable Ink personalizes every customer engagement through automation and artificial intelligence. The world’s most innovative brands rely on Movable Ink to maximize revenue, simplify workflow and achieve the optimal customer experience. Headquartered in New York City with 600 employees, Movable Ink serves its global client base with operations throughout North America, Central America, Europe, and Australia.
Movable Ink's Top Stability & Growth Strengths
Investor Backing & Capital Strength: The June 2025 definitive agreement for acquisition by STG, with leadership continuity noted at announcement and a sizable employee footprint, points to a platform investment with resources to scale. Earlier unicorn-level financing further underscores access to capital supporting ongoing expansion.
Innovation-Driven Growth: Regular releases through late 2025 and 2026—such as Da Vinci enhancements and the launch of Programmatic CRM with AI/agentic capabilities—signal sustained R&D and product momentum. Feature and suite expansion across email, mobile, and web indicate a growth engine rooted in innovation.
Strong Hiring & Retention: Mid-2026 career pages and third-party trackers show active open roles and “we’re hiring” messaging, implying continued team expansion. Public materials reference a global workforce across multiple regions, consistent with selective growth.

Commerce (Nasdaq: CMRC) empowers businesses to innovate, grow, and thrive through an open, AI-driven commerce ecosystem. As the parent company of BigCommerce, Feedonomics, and Makeswift, we help brands unlock the full potential of their data, connect systems, and deliver seamless, personalized experiences across every channel. Visit commerce.com or follow us for more. #PoweredByCommerce

Commerce's Top Stability & Growth Strengths
Profitability: GAAP net income turned positive in Q1 and Q2 2026, with improving operating metrics versus prior‑year losses. This points to healthier unit economics even as top‑line growth is modest.
Innovation-Driven Growth: Investment in AI‑driven “agentic commerce,” LLM data enrichment, and B2B operational agents—alongside embedded payments—signals a roadmap aimed at future monetization. Double‑digit GMV growth and sequential NRR improvement indicate these capabilities are supporting healthier platform engagement.
Strategic Partnerships: Expanded Stripe capabilities and PayPal‑embedded payments, plus ecosystem activity across BigCommerce, Feedonomics, and Makeswift, are highlighted as growth enablers. These integrations support attach‑rate and monetization theses tied to payments and partner services.

Datadog (NASDAQ: DDOG) is a global SaaS business, delivering a rare combination of growth and profitability. We are on a mission to break down silos and solve complexity in the cloud age by enabling digital transformation, cloud migration, and infrastructure monitoring of our customers' entire technology stacks. Built by engineers, for engineers, Datadog is used by organizations of all sizes...

Datadog's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is accelerating, with early‑2026 results exceeding the prior year’s pace and the full‑year outlook raised to reflect continued momentum. Large‑customer additions further reinforce top‑line expansion at scale.
Healthy Cash Flow: Operating and free cash flow remain substantial, including strong generation in Q2 2026 and across FY2025. This liquidity provides flexibility to invest while sustaining growth.
Innovation-Driven Growth: New AI‑powered capabilities—such as Bits AI offerings, GPU Monitoring, and an agent builder—were launched around Q1–Q2 2026 and at DASH 2026, supporting usage and upsell. Broader multi‑product adoption and growth in high‑ARR cohorts are highlighted across recent updates.
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Recent quarters delivered double-digit year-over-year gains in revenue (Q1 +15%, Q2 +14%), and management raised the 2026 outlook to about 9–10% revenue growth after results exceeded guidance. This builds on 2025’s double-digit Q4 growth and an 8% full‑year revenue increase.
Diversified Revenue Streams: Strength across consumer brands, sustained expansion in B2B, and contributions from the EG Advertising business are cited as key growth engines. This spread across channels and monetization types supports continued momentum.
Strategic Partnerships: Ongoing expansion in B2B partnerships and the unification of B2B and supply leadership aim to tighten execution, with new distribution wins such as Allegiant and a pending CarTrawler acquisition reinforcing partner-led growth. These moves broaden reach and deepen platform integration.

Vantor is forging the new frontier of spatial intelligence to unlock a more autonomous, interoperable world. We empower decision makers and operators with the clarity they need to navigate what’s happening now and shape what’s coming next. Our AI-powered spatial intelligence platform fuses data from the world’s highest-resolution satellites with real-time sensor feeds from space, air, and ground to create...
Vantor's Top Stability & Growth Strengths
Innovation-Driven Growth: Recent moves pair a planned constellation expansion that combines higher-resolution imaging with higher revisit rates with an AI-centric platform and new 3D offerings. Together, these signal movement up the value chain toward higher-margin software and systems.
Market Expansion: Statements highlight expanding international activity, including a Bundeswehr-focused joint effort, more than a dozen new European customers in 2025, and 60+ government partners. These point to growing geographic reach and customer adoption.
Strategic Partnerships: Collaborations such as a German JV with Rheinmetall for ISR data integration and a build partnership with BAE Systems on next-generation satellites indicate deepening ecosystem ties. Such alliances can accelerate access to new programs and markets.
Clear Street’s mission is to give every sophisticated investor access to every asset, in every market, through a unified platform built for speed, transparency and scale. We give our clients the technology, tools, and service once reserved for the largest institutions, rebuilt with modern infrastructure. Our single, cloud-native, end-to-end capital markets platform powers investor growth today and is transforming how they...

Clear Street's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as accelerating sharply, with filings showing substantial year-over-year gains through 2024 and the first nine months of 2025, and independent estimates pointing to a billion‑dollar run rate in 2025. These trends align with rising client activity and balances disclosed alongside product launches.
Investor Backing & Capital Strength: New equity financing in January 2026 co‑led by Baillie Gifford and SBI Holdings, reports of a multibillion‑dollar pre‑IPO valuation, and outstanding senior notes expand financial capacity for scaling. These signals suggest ample capital to support continued build‑out and pre‑IPO positioning.
Market Expansion: Licenses in Europe, an APAC entry via the Boom Securities deal, and a trading app for sophisticated individual investors broaden both geography and customer segments beyond institutional prime brokerage. Cross‑margin and digital‑asset initiatives further indicate expansion into adjacent markets.
.jpg)
At Braze, we believe in the passion of our people. We seek to ignite that passion by setting high standards, championing teamwork, and creating work-life harmony. We thrive when people add their unique perspectives to our ever-growing teams—and we strive to empower you to make an impact that fuels both you, and our business.

Braze's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue reached $738.2M in FY2026 and $211.0M in Q1 FY2027, with four consecutive quarters of organic acceleration. Guidance was raised to $895–$899M for FY2027, signaling continued double-digit expansion.
Customer Loyalty & Retention: Dollar-based net retention remained healthy in FY2026 and edged higher in Q1 FY2027, while large-customer counts grew and remaining performance obligations reached roughly $1.08B. These trends point to expanding spend within the base and solid revenue visibility.
Healthy Cash Flow: Non-GAAP operating income turned positive in FY2026 and stayed positive in Q1 FY2027, with free cash flow positive in both periods. Improving operating leverage supports ongoing investment alongside growth.

Samsara (NYSE: IOT) is the pioneer of the Connected Operations® Platform, which is an open platform that connects the people, devices, and systems of some of the world’s most complex operations, allowing them to develop actionable insights and improve their operations. With tens of thousands of customers across North America and Europe, Samsara is a proud technology partner to the...

Samsara's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue and ARR are expanding rapidly at scale, with Q1 FY27 revenue near $479M and ARR approaching $2B while full‑year guidance still calls for further growth. Continued expansion among $100K+ and $1M+ customer cohorts reinforces momentum.
Profitability: The company reports consecutive GAAP‑profitable quarters alongside improving non‑GAAP operating and free‑cash‑flow margins, indicating operating leverage. Management also expects GAAP profitability for the full FY27.
Innovation-Driven Growth: New products such as AI Multicam, Asset Maintenance, Asset Tags, Connected Training, and Connected Workflows are contributing materially to net new ACV and deepening multi‑product adoption. A large and growing data platform and interest in Operational AI further catalyze expansion.
Sonar provides the essential verification layer for the AI-driven development era, ensuring all code—whether human-written or AI-generated—is code you can trust. Today, AI coding tools are generating explosive volumes of code. This has created an "engineering productivity paradox" : faster code writing doesn't automatically lead to faster, safer software delivery. The new bottleneck is verification. Sonar solves this. Integrating code quality and...

Sonar's Top Stability & Growth Strengths
Product Line Growth: Recent launches tied to AI-era development—such as Sonar Vortex, the SonarQube Remediation Agent, a unified SonarQube CLI, and expanded code‑security capabilities—signal an actively expanding product suite. The acquisition of Gitar adds AI‑native code review to the platform, indicating continued investment and category reach.
Market Expansion: Expansion moves include establishing a regional headquarters in Singapore and positioning the platform as an independent verifier layer across AI models and common SDLC tools. Marquee adopters and broad Fortune 100 penetration suggest reach across industries and geographies.
Strong Market Position & Advantage: Scale indicators such as 7M+ developers across 400k+ organizations, ‘750B+ lines of code analyzed daily,’ and logos like Nvidia, AstraZeneca, and Ford point to an entrenched position. Headcount rising from roughly 700 (2023) to about 1,000 (2026, estimate) further supports operational capacity at scale.
Rubrik (NYSE: RBRK), the Security and AI Operations Company, leads at the intersection of data protection, cyber resilience, and enterprise AI acceleration. Rubrik Security Cloud delivers complete cyber resilience by securing, monitoring, and recovering data, identities, and workloads across clouds. Rubrik Agent Cloud accelerates trusted AI agent deployments at scale by monitoring and auditing agentic actions, enforcing real-time guardrails, fine-tuning...

Rubrik's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising rapidly across recent periods, with FY2026 results and the subsequent quarter both showing sharp year-over-year increases and strong subscription-led momentum. Management raised the FY2027 outlook following the latest quarter, underscoring continued demand.
Healthy Cash Flow: Free cash flow is meaningfully positive and improving at scale, including a healthy margin in Q1 FY2027 and a large year-over-year increase in FY2026. Improving subscription contribution margins indicate growing operating leverage.
Strong Market Position & Advantage: Independent analyst recognitions place the company among market Leaders for backup/data protection and cyber recovery, often highlighted for vision. Expanding large-customer cohorts and post-IPO scale further reinforce competitive standing.
Yext (NYSE: YEXT) is the enterprise agentic marketing platform. Built on the world's most comprehensive structured data platform for local businesses, Yext gives brands and their partners the visibility intelligence to win every moment of discovery – across AI and traditional search. Yext's API-first architecture connects structured data to APIs, MCP servers, and generative interfaces, so partners and developers can...

Yext's Top Stability & Growth Strengths
Profitability: GAAP profitability and expanding Adjusted EBITDA are evident, with FY2026 delivering over $100M in Adjusted EBITDA and profitability continuing in Q1 FY2027. Margin gains reflect efficiency actions and operating leverage noted in recent periods.
Healthy Cash Flow: Cash generation is solid, with FY2026 producing $53.3M in free cash flow and Q1 FY2027 adding roughly $37M. Consistent positive cash flow supports ongoing operations and strategic initiatives.
Investor Backing & Capital Strength: The company completed a $140M Dutch‑auction tender repurchasing 24.3M shares and increased its open‑market repurchase authorization by $100M. These actions signal confidence and capacity to return capital.
MarketAxess is on a journey to digitally transform one of the world's largest financial markets, enabling the shift from analog, phone-based trading to a fully electronic marketplace. Why does this matter? Because our platform makes trading fixed-income more accessible, ultimately improving transparency, efficiency and competition in the marketplace. Changing the way an established industry transacts is no easy feat. There...

MarketAxess's Top Stability & Growth Strengths
Diversified Revenue Streams: Services, post-trade, data, and technology lines showed steady growth with records in 2025 and Q2 2026, and revenue outside U.S. credit plus emerging markets/eurobonds expanded. These trends indicate multiple monetization pillars beyond core U.S. credit.
Strong Market Position & Advantage: Market presence in institutional credit e-trading remains prominent, with leadership in all-to-all and portfolio trading and rising adoption in key workflows. Trading updates cited increased portfolio-trading activity and share alongside broad platform scale.
Innovation-Driven Growth: Newer protocols and tools—such as portfolio trading, block trading, Mid-X, CP+ pricing, and data solutions—are gaining traction and setting record activity levels. Product innovation appears to be a key driver of client adoption across credit workflows.

LogicMonitor® is the AI-first hybrid observability platform powering the next generation of digital infrastructure. LogicMonitor delivers complete visibility and actionable intelligence across on-premises, cloud, and edge environments. By anticipating issues before they strike, optimizing resources in real time, and enabling faster, smarter decisions, LogicMonitor helps IT and business leaders protect margins, accelerate innovation, and deliver exceptional digital experiences without compromise....

LogicMonitor's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is described as rising from over $300M in 2025 to over $400M by mid-2026, alongside large-scale telemetry usage that signals expanding adoption. This trajectory indicates sustained top-line expansion through 2026.
Innovation-Driven Growth: AI-led capabilities such as Edwin AI are portrayed as a meaningful driver of bookings with rapid recurring revenue momentum, and the company is advancing an “Autonomous IT” roadmap. Continued AI feature launches through 2026 point to product-led expansion.
Investor Backing & Capital Strength: An $800M financing in late 2024 at around a multi‑billion valuation provides resources to accelerate platform expansion, acquisitions, and entry into new markets. This capital base supports ongoing scaling initiatives.
Justworks is a cloud-based software platform that takes the busyness out of growing a business and alleviates the unknown. We've combined a simple platform and exceptional 24/7 customer service to help entrepreneurs and businesses grow with confidence by giving them access to corporate-level benefits, automated payroll, HR tools, and compliance support— all in one place.
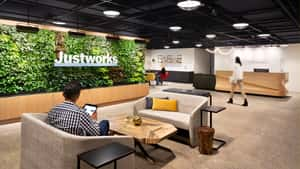
Justworks's Top Stability & Growth Strengths
Strong Revenue Growth: Recent disclosures cite being on track to do more than $500M in net revenue for the fiscal year ending May 31 and a rise in a contribution metric from roughly $140M (2022) to about $350M (2024). Earlier filings also reported 32% year-over-year revenue growth in FY2021, indicating multi-year top-line expansion.
Product Line Growth: The company expanded beyond its core PEO with a standalone Payroll product, Employer of Record capabilities in Canada, and a 2026 ICHRA partnership with Thatch. These additions signal investment in adjacent offerings that can drive incremental growth.
Market Expansion: Customer counts progressed from nearly 9,000 (2022) to 12,000+ (2024/2025) and to about 15,000 in a 2026 CEO note, alongside 30% more new customers year over year. Operating throughput reached $31B+ in payroll processed and 268K+ W‑2s in 2025, consistent with a broader footprint.
Fusion Risk Management is recognized as the most innovative and fastest growing provider of cloud-based enterprise software for business continuity risk management, IT disaster recovery and crisis management. Fusion is transforming the industry and has been named a leader in Gartner's Magic Quadrant for Business Continuity Management software.

Fusion Risk Management's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A 2023 strategic growth investment from Great Hill Partners, with Vista retaining a minority stake, is presented as funding to accelerate product innovation and go-to-market. This signals ample resources to support expansion initiatives into 2025–2026.
Product Line Growth: Recent launches such as the Enterprise Resilience Decision System (2026), Recovery Optimization (late 2025), and AI-enabled planning tools indicate an active roadmap and expanded capabilities. This cadence points to ongoing product investment aimed at capturing more use cases.
Market Expansion: Leadership additions focused on scale—a new CMO (Mar 2026), CPO (Feb 2026), an executive to drive international growth (Jan 2026), and a CFO (Dec 2025)—along with active openings across sales, product, data/AI, and marketing, suggest widening go-to-market reach. Stated use by 400+ enterprises and inclusion as a Leader on G2’s Winter 2026 ERM Grid reinforce a growing presence.



