

Top Tech Companies in London (7,386)
CDW Corporation is a leading multi-brand provider of information technology solutions to business, government, education and healthcare customers in the United States, the United Kingdom and Canada. A Fortune 500 company and member of the S&P 500 Index, CDW helps its customers to navigate an increasingly complex IT market and maximize return on their technology investments. For more information about...

CDW's Top Stability & Growth Strengths
Strong Revenue Growth: Net sales rose 6.8% in 2025 to $22.4B and accelerated to 9.2% in Q1 2026 and 10.0% in Q2 2026, with non‑GAAP EPS also increasing. Management continues to target outgrowing the U.S. IT addressable market by 200–300 bps.
Diversified Customer Base: Growth was broad across Commercial (+9.2%), Government (+13.6%), Education (+0.7%), and international “Other” (+22.9%) in Q2 2026, with 2025 gains led by Small Business, Corporate, and UK/Canada. This breadth helps smooth spending cycles and supports share gains.
Healthy Cash Flow: Regular capital returns continued, highlighted by a $0.63 quarterly dividend declared for September 10, 2026. Operating income and non‑GAAP earnings increased, indicating ongoing cash generation to fund dividends.
CoreWeave, the AI Hyperscaler™, delivers a cloud platform of cutting-edge software powering the next wave of AI. The company's technology provides enterprises and leading AI labs with cloud solutions for accelerated computing. Since 2017, CoreWeave has operated a growing footprint of data centers across the US and Europe. CoreWeave was ranked as one of the TIME100 most influential companies and...

CoreWeave's Top Stability & Growth Strengths
Strong Revenue Growth: Reported revenue rose from $1.9B in 2024 to $5.1B in 2025, with early‑2026 quarters continuing triple‑digit year‑over‑year increases. These disclosures indicate a steep, ongoing acceleration in scale.
Strategic Partnerships: Multi‑year, multi‑billion‑dollar agreements with Meta, Anthropic, Jane Street, and expanded OpenAI commitments point to durable, large‑scale utilization. A deepened NVIDIA collaboration, including early deployments of GB200/GB300 and plans to accelerate AI “factory” buildouts, supports access to cutting‑edge capacity.
Investor Backing & Capital Strength: Significant financing and market recognition—including a $1.1B Series C, large credit and notes facilities, and inclusion in the Nasdaq‑100—underscore strong capital access. This funding underpins rapid data‑center expansion and GPU procurement.
Celonis makes processes work — for people, companies, and the planet. Powered by process mining and AI, the Celonis Process Intelligence Platform integrates process data and business context to create a living digital twin of business operations. We enable thousands of companies worldwide to understand how their business actually runs and, together with their partners, build intelligent solutions that transform...

Celonis's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent market-share analysis places Celonis at the front of its category while the market itself expands. This positioning suggests the company is capturing growth in a segment it leads.
Future-Ready Strategy: External recognition for long-term growth potential signals confidence in Celonis’s strategy, innovation, and talent pipeline. This points to preparedness as the space broadens from process mining into process intelligence and AI-enabled workflows.
Strategic Partnerships: A new alliance with a major data and AI platform provider expands product integrations and go-to-market reach into enterprise AI workflows. Such ecosystem momentum supports broader adoption and commercial expansion.
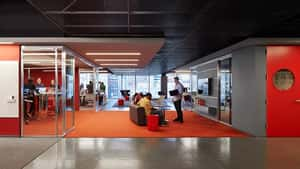
We are a global investment research and financial data company with 40-plus offices across North America, Europe, Australia, and Asia. Our products and services are used daily by individual investors, financial advisors, asset managers, retirement plan providers, and institutional investors. We provide data, research, and analysis across managed investment products, publicly listed companies, private capital markets, debt securities, and real-time...
Morningstar's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue up 9.6% year over year in Q2 2026 (6.8% organic; 8.2% excluding product sunsets), with 2025 up 7.5% and year‑to‑date 2026 up 10.2% on a reported basis. Growth is led by Morningstar Credit and core data/software platforms such as Morningstar Direct and PitchBook.
Profitability: Operating and adjusted operating margins expanded in Q2 2026 alongside a 29% rise in adjusted diluted EPS to $3.10, and 2025 saw increases in operating income and adjusted operating income. These gains were supported by stronger contribution from Credit and the accretive effect of the CRSP acquisition.
Healthy Cash Flow: Free cash flow and operating cash flow increased sharply in Q2 2026, with free cash flow nearly doubling year over year. This improved cash generation coincided with active buybacks and dividends.
Genius Sports is the layer between what happens on the field and how the world engages with it. Our solutions across the global sports ecosystem are underpinned by our next generation big data and artificial intelligence platform, GeniusIQ. By ingesting and computing multiple real-time data feeds, GeniusIQ powers a wide range of functions and applications across sports performance and officiation, fan engagement,...

Genius Sports's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue accelerated across early 2026, with Q2 performance surpassing guidance and prompting management to raise the full‑year outlook to around $1 billion of revenue and higher adjusted EBITDA. Guidance increases followed multi‑quarter momentum from 2025 into 2026.
Diversified Revenue Streams: Media Technology grew sharply with stronger advertising demand and the Legend acquisition, while expansion into prediction markets adds a new category beyond core betting data. This mix shift broadens exposure beyond a single segment and supports the higher full‑year targets.
Innovation-Driven Growth: New offerings such as GeniusIQ, Moment Engine, and BetVision—alongside price‑led renewals and expanded services in Betting Technology—are identified as key drivers of segment gains. Product momentum in ad tech and data‑rich streaming is contributing meaningfully to growth.
Nexthink is the global leader in digital employee experience management. Our platform empowers IT teams with real-time visibility, analytics, and automation to proactively detect and resolve issues across any application, device, or network—before they affect employees. By shifting IT from reactive problem-solving to continuous optimization, Nexthink enables more than 1,300 organizations to create productive, seamless, and satisfying digital workplaces for...

Nexthink's Top Stability & Growth Strengths
Strong Market Position & Advantage: Repeated Leader placements in Gartner’s DEX Magic Quadrant (2024–2026) and Forrester’s 2024 EUEM Wave indicate durable competitive standing and sustained category momentum. These recognitions coincide with communications citing 1,200–1,500+ customers and 20M+ endpoints, underscoring broad enterprise adoption.
Product Line Growth: New offerings such as Adopt on Infinity (2025) and the Spark personal IT agent (2026), plus integrations like GoTo/Rescue and a government-focused AWS Marketplace listing, expand use cases and routes to market. The 2024 acquisition of AppLearn further broadened capabilities into digital adoption.
Investor Backing & Capital Strength: A late‑2025 majority investment by Vista Equity Partners at an approximately $3B valuation signals strong external confidence and provides resources for scaling. This step-up from the 2021 round supports continued product and go‑to‑market execution.
At Shield AI, you won't wait years to see your work reach the field. You'll build hardware and software that operates in the real world right now, in the hands of the people who depend on it. Hivemind, our AI pilot, has been flying since 2018. It has flown more than 30 platforms, including an F-16, and it now sits under...
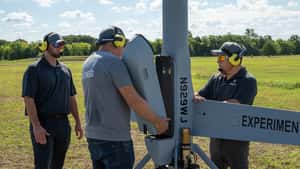
Shield AI's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is on a clear upward trajectory, with estimates rising from 2024 through 2025, leadership guiding to a substantially larger 2026, and a stated path toward $1B by 2028. This momentum is tied to increasing orders, expanding programs, and a growing mix of software and systems.
Investor Backing & Capital Strength: A multi‑billion‑dollar capital package closed in March 2026, including a $1.5B Series G at a $12.7B valuation plus additional preferred equity and a delayed‑draw facility. This financing depth provides runway to scale autonomy software, aircraft programs, and the Aechelon acquisition.
Market Expansion: Operations and sales expanded internationally with new contracts across allies including Romania, Japan, Greece, and Canada, while U.S. traction includes Air Force CCA autonomy selections and a Navy contract to further develop X‑BAT. Over time, these moves broaden geographic reach and platform adoption.

Liftoff is a leading AI-powered performance marketing platform for the mobile app economy. Our end-to-end technology stack helps app marketers acquire and retain high-value users, while enabling publishers to maximize revenue across programmatic and direct demand. Liftoff’s solutions, including Accelerate, Direct, Monetize, Intelligence, and Vungle Exchange, support over 6,600 mobile businesses across 74 countries in sectors such as gaming, social, finance,...

Liftoff's Top Stability & Growth Strengths
Strong Revenue Growth: Management disclosed 11 consecutive quarters of top-line expansion as of Q2 2026, with guidance indicating continued increases post‑IPO. Observations across filings and coverage describe multi‑quarter momentum rather than a one‑off spike.
Investor Backing & Capital Strength: A completed IPO and a prior minority investment from General Atlantic alongside Blackstone signal institutional confidence and provide balance‑sheet flexibility. Proceeds were used in part to reduce debt, supporting capacity for further expansion.
Innovation-Driven Growth: The Cortex AI platform is presented as a core differentiator driving performance gains across a unified DSP/SSP stack. Product updates and shortened learning cycles are highlighted as catalysts for advertiser and publisher adoption.
HiBob helps modern, mid-size businesses transform the way they manage people, giving HR and managers all they need to connect, engage, develop, and retain top talent. Since 2015, we’ve achieved consecutive triple-digit year-over-year growth, all backed by our amazing team of Bobbers from across the globe, making us the choice HRIS of over 4000 midsize and multinational companies. Our HR platform...
HiBob's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is characterized as moving from roughly $197M in 2025 to $250M+ by 2026, alongside customer and user counts rising from ~4,400/1.1M to 5,000+/1.3M through 2025. These directional milestones point to ongoing top-line expansion even without audited financials.
Market Expansion: The suite broadened with the Mosaic FP&A acquisition and the launch of Bob Finance in late 2025, complementing prior payroll moves and a Toronto office opening to deepen North American reach. These steps expand cross-sell/upsell potential and support penetration beyond core HR.
Investor Backing & Capital Strength: Successive $150M raises in 2021, 2022, and 2023 and a valuation reported near $2.7B by 2023 leave the company well capitalized (≈$574M total). This capital base enables continued product investment and go-to-market scale.

ZS is a management consulting and technology firm that partners with companies to improve life and how we live it. We transform ideas into impact by bringing together data, science, technology and human ingenuity to deliver better outcomes for all. Founded in 1983, ZS has more than 15,000+ employees in over 40 offices worldwide.
ZS's Top Stability & Growth Strengths
Market Expansion: Headcount and footprint are described as rising to more than 15,000 employees across 40-plus offices, alongside concrete new sites in Hyderabad and a completed Chicago buildout—signals of geographic and capacity expansion. These moves indicate confidence in demand across key delivery hubs.
Innovation-Driven Growth: A dedicated Platforms & Products unit, the ZAIDYN portfolio, and AI-agent initiatives point to sustained investment in productized, AI-enabled offerings. Capability-deepening acquisitions (Digital Additive in 2024 and Torrent Consulting in 2025) further strengthen CRM and multi‑cloud life‑sciences solutions.
Strategic Partnerships: An expanded Salesforce collaboration around Agentforce and recognition as Databricks 2025 Life Sciences Partner of the Year suggest momentum in data/AI ecosystems. These alliances position the firm to capture spend where CRM, data, and AI converge in healthcare and life sciences.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Subscription revenue reached $3.877B in Q2 2026, growing strongly year over year, with total revenue also advancing. The company raised its full-year 2026 subscription outlook to $15.76–$15.78B and guided continued double-digit growth into Q3.
Product Line Growth: “ServiceNow AI” surpassed $1B in ACV in Q2 2026, acting as a catalyst for deal activity and upsell. Newer AI capabilities layered onto core workflows are described as adding incremental momentum.
Resilient & Sustainable Growth: Current and total RPO climbed to $13.20B and $29.0B, respectively, indicating strong contracted demand ahead. The number of customers above $5M in ACV increased meaningfully, supporting durable multi‑year expansion.
Webflow empowers teams — from startups to the Fortune 500 — to design, build, and grow for the web, all without writing a single line of code. Simply put: we’re changing the way the internet gets built. Instead of relying on long dev cycles or heavy engineering support, Webflow lets teams move from idea to launch faster — bringing creativity...

Webflow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is portrayed as scaling from near $100M ARR around the 2022 raise to roughly double by 2023, with later summaries citing 2024 revenue above $200M. These signals indicate continued commercial expansion beyond the 2022 baseline.
Investor Backing & Capital Strength: Capital position is described as robust, with a $4B valuation tied to a sizable 2022 round and substantial total funding. This runway underpins ongoing product and upmarket investments.
Innovation-Driven Growth: Product scope is expanding via acquisitions (e.g., AI personalization/optimization) and new AI features, alongside a resiliency roadmap after the July 2025 incident. These moves are positioned to support larger‑scale usage and enterprise adoption.
At Capital One, we think and work like a tech company, using our digital fluency to transform everything about the customer experience. We’re bending data to our will, and turning a stodgy industry on its head. That’s reflected in our ranking as the number one business technology innovator in the U.S. in the 2016 InformationWeek Elite 100.
Capital One's Top Stability & Growth Strengths
Strong Revenue Growth: Q2 2026 total net revenue rose 4% sequentially to $15.9 billion. Integration of Discover and Brex contributed to higher non‑interest income and broader payments capabilities.
Profitability: Q2 2026 net income reached $3.0 billion, up from $2.2 billion in Q1 2026, alongside a net interest margin of 8.01%. Management also cited strong credit performance, including a $662 million reserve release.
Market Expansion: Acquisition‑driven scale is broadening reach, with the Discover deal (closed May 18, 2025) and Brex (closed April 7, 2026) adding network and corporate card/spend‑management capabilities. Balance‑sheet growth continued in Q2 2026 as period‑end loans rose 2% to $457.2 billion and total assets reached $673.8 billion.
CAIS is the leading alternative investment platform for independent financial advisors. The CAIS platform powers the pre-trade, trade, and post-trade lifecycle of alternative investments providing financial advisors and alternative asset managers a single operating system for scale and efficiency. CAIS serves over 2,000 wealth management firms that support more than 50,000 financial advisors who oversee approximately $6 trillion in end-client assets....
CAIS's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A sizable Series D led by Vista Equity Partners valued the company above $2 billion and brought total capital raised close to $600 million. This capital is described as fueling platform expansion and scaling of technology and AI capabilities.
Strong Revenue Growth: Company disclosures highlight strong multi‑year organic revenue growth alongside notable increases in transaction activity and platform assets in 2026. The pattern points to operating momentum beyond valuation headlines.
Market Expansion: The platform has expanded distribution by onboarding hundreds of RIAs and independent broker‑dealers since 2025 and now serves a large network of wealth firms and advisors. Added strategies from alternative asset managers and rising usage in structured solutions further indicate broader reach across the advisor ecosystem.
.png)
GRAIL is a healthcare company whose mission is to detect cancer early, when it can be cured. GRAIL is using the power of high-intensity sequencing, population-scale clinical studies, and state-of-the-art computer science and data science to enhance the scientific understanding of cancer biology, and to develop and commercialize pioneering products.
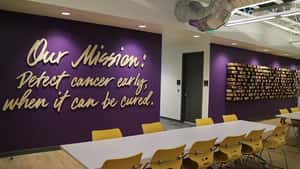
GRAIL's Top Stability & Growth Strengths
Strong Revenue Growth: Galleri and total revenue have risen consistently, with full-year 2025 up 17% and U.S. Galleri up 26%, followed by Q1–Q2 2026 total revenue gains of 28% and 26% alongside 50% and 35% volume growth. This cadence, including Q4 2025 Galleri revenue up 31%, indicates sustained commercial momentum after the June 2024 spin‑off.
Strategic Partnerships: Channel and platform integrations such as Epic EHR and Quest Diagnostics, plus collaborations like Samsung for Asian commercialization, are expanding access and streamlining ordering. Additional distribution wins (e.g., Priority Health employer plans and digital health channels) reinforce multi‑channel penetration for Galleri.
Investor Backing & Capital Strength: The company reports a substantial cash balance (~$861.6M as of Q2 2026) and closed a $110M equity financing with Samsung, bolstering financial flexibility. Public listing post‑spin‑off further enhances capital‑markets access to fund trials and commercialization.

CWAN was founded on a simple belief: investment professionals deserve modern technology that actually works for them. Not legacy systems that slow them down. Not fragmented data that creates confusion. But one comprehensive platform that gives you complete visibility and crystal-clear insights. The result? Investment management that works as seamlessly as your investment strategy. Since our founding in 2004, CWAN has been...

Clearwater Analytics (CWAN)'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is accelerating sharply across late 2025 and early 2026, with multiple consecutive quarters of substantial year-over-year gains. Annualized recurring revenue expanded materially over the same periods, reinforcing momentum.
Customer Loyalty & Retention: Client relationships appear sticky, with strong gross retention and ongoing net expansion across the base. Management also notes over 2,500 clients by year-end 2025, pointing to low churn and healthy upsell.
Healthy Cash Flow: Operating cash flow is described as strong alongside rising adjusted EBITDA with healthy margins. These trends suggest increasing capacity to fund integration and platform investments.

Taskrabbit is a marketplace platform that conveniently connects people with Taskers to handle everyday home to-do’s, such as furniture assembly, handy work, moving help, and much more. Acquired by IKEA Group - the world’s largest furniture retailer - in 2017 At Taskrabbit, we want to make your neighborhood a little more familiar. Whether it’s a handyman (or woman!), a housecleaner, moving...

Taskrabbit's Top Stability & Growth Strengths
Market Expansion: Nationwide availability in the U.S., ongoing city-level rollouts, and operations across eight countries indicate a widening footprint. Recent announcements highlight additional service areas and partner activations through 2025–2026, pointing to sustained reach expansion.
Product Line Growth: The acquisition of Dolly and its July 2026 rebrand to Taskrabbit Delivery extend capabilities into big‑and‑bulky moving and retail logistics. Additions like Taskrabbit for Business, partner pages, and embedded checkout experiences broaden offerings beyond core household tasks.
Strong Revenue Growth: Leadership communications describe substantial multi‑year revenue increases, supported by earlier strong year‑over‑year gains. Reported momentum in moving‑related bookings and seasonal task surges in select metros reinforces underlying demand growth.

At Teya, we believe small, local businesses are the heartbeat of every community. Teya was founded to help small, local businesses thrive. We exist to make business smoother, simpler, and more rewarding for the people who keep our communities alive. That means exceptional support, intuitive solutions, and a team truly invested in our Members’ success. To us, they’re more than customers...
Teya's Top Stability & Growth Strengths
Market Expansion: Expansion into Spain and Italy in 2026 brought operations to nine European markets, with launches following earlier pilots. Announced plans for further European rollout reinforce active scaling.
Product Line Growth: New offerings such as Tap to Pay on iPhone, the Teya Pro terminal with instant settlement, and a rebuilt Business Account indicate ongoing feature velocity. Additional products like Teya Cash Advance broaden ways to deepen merchant engagement.
Strategic Partnerships: Partnerships with Liberis, YouLend, iwoca, and Flowpay embed SME financing into the platform across multiple countries. These tie-ups expand distribution and signal a wider monetization toolkit within the ecosystem.
Bringg is the leading Delivery Management Platform -- optimizing last mile delivery, fulfillment, and returns for retailers and carriers worldwide. Bringg transforms delivery into a competitive advantage for 800+ customers, increasing order capacity, reducing costs, and ensuring branded customer experiences, handling over 200 million orders annually.

Bringg's Top Stability & Growth Strengths
Innovation-Driven Growth: Public release notes through mid-2026 show ongoing feature delivery across Dispatch/Planning and Order Manager, and the April 2025 launch of Dynamic Delivery Slots underscores continued platform extension. This cadence indicates active development in support of live enterprise use cases.
Strategic Partnerships: The company continues to emphasize its carrier network and ecosystem integrations, including an Uber Direct tie-in and ongoing Zenkraft activity on Salesforce AppExchange in 2025–2026. These connections suggest durable routes to market and expanded solution coverage.
Market Expansion: Appointment of a new SVP/GM for EMEA in April 2026, alongside continued market education (e.g., State of the Last Mile research), points to a regional push and demand-generation focus. Related partner activity (such as the UK extension of Uber Direct) aligns with widening geographic reach.
Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising briskly, with the latest quarter up year over year and full‑year FY2026 guidance raised for both revenue and ARR. Prior billings and deferred revenue growth indicate healthy demand heading into FY2026.
Strong Market Position & Advantage: Independent analyst evaluations place the company as a leader in SSE/SASE and note frequent inclusion on enterprise shortlists. A broad global footprint and regulatory certifications bolster competitiveness in regulated and international markets.
Product Line Growth: Expansion in newer offerings—such as Data Security, AI‑focused modules, and Zero Trust Branch—shows meaningful traction. Metered, non‑seat‑based solutions accounted for a sizable share of new ACV, suggesting broader monetization beyond core seats.



